

FCT Earnings Analysis: Gearing Is 38.7% Today and 36.8% After the White Sands Repayment. What Is Still Missing?
FCT paid a record 12.35 cents with its malls 99.7% committed. Here is what drove the result, what the White Sands repayment changes on the balance sheet, and what it has not changed yet.
Frasers Centrepoint Trust’s gearing is 38.7%, which is 3.7 percentage points above the ceiling I use, in the same results that delivered a record distribution of 12.35 cents per unit. If you hold FCT for income, both facts belong to you, and they point in different directions. This piece sets out what each one means for the income you are counting on.
Two kinds of FCT holder will read this. One bought years ago and has watched the payout creep up. The other is looking at a trailing yield of 5.78% at SGD 2.11 and wondering whether this is the entry. I tested the results presentation for the year ended 30 September 2026 against my gates, and both readers get the same answer, applied to their own cost.
What This Piece Does
It sets out what drove the record distribution, and why per-unit growth was slower than total growth.
It tests the balance sheet against my gates: gearing, interest cover and occupancy.
It works through what the White Sands repayment changes and what it leaves open.
It shows what the result means for a holder from earlier years and for fresh capital.
The results and my zone verdict are free to read. The gate-by-gate working, the debt analysis and the soft flag breakdown are in the members’ half. Nothing here is a recommendation. This is my forensic stance, based on my personal tracking.

What This Piece Does
What the Results Say
The record is real, and so is the gap
Is the growth coming from the malls?
What is being rebuilt?
Dividend Trajectory
Iggy’s Insights
Valuation Table
Where FCT Sits on My Screen
The Balance Sheet Against My Gates
Gearing: how far over, and what the repayment does
Iggy’s Insights
Interest cover: it clears, but the jump needs a reason
Debt: how much of it is fixed
The Zone, and What Would Change It
Soft flags: 0.5 weighted.
Why the minus.
What clears it.
What the Zone 4 verdict does and does not say
Legacy Holders vs. Fresh Capital
What I Am Watching Next, Without Predicting
Iggy’s Forensic Read
What the Results Say
The record is real, and so is the gap
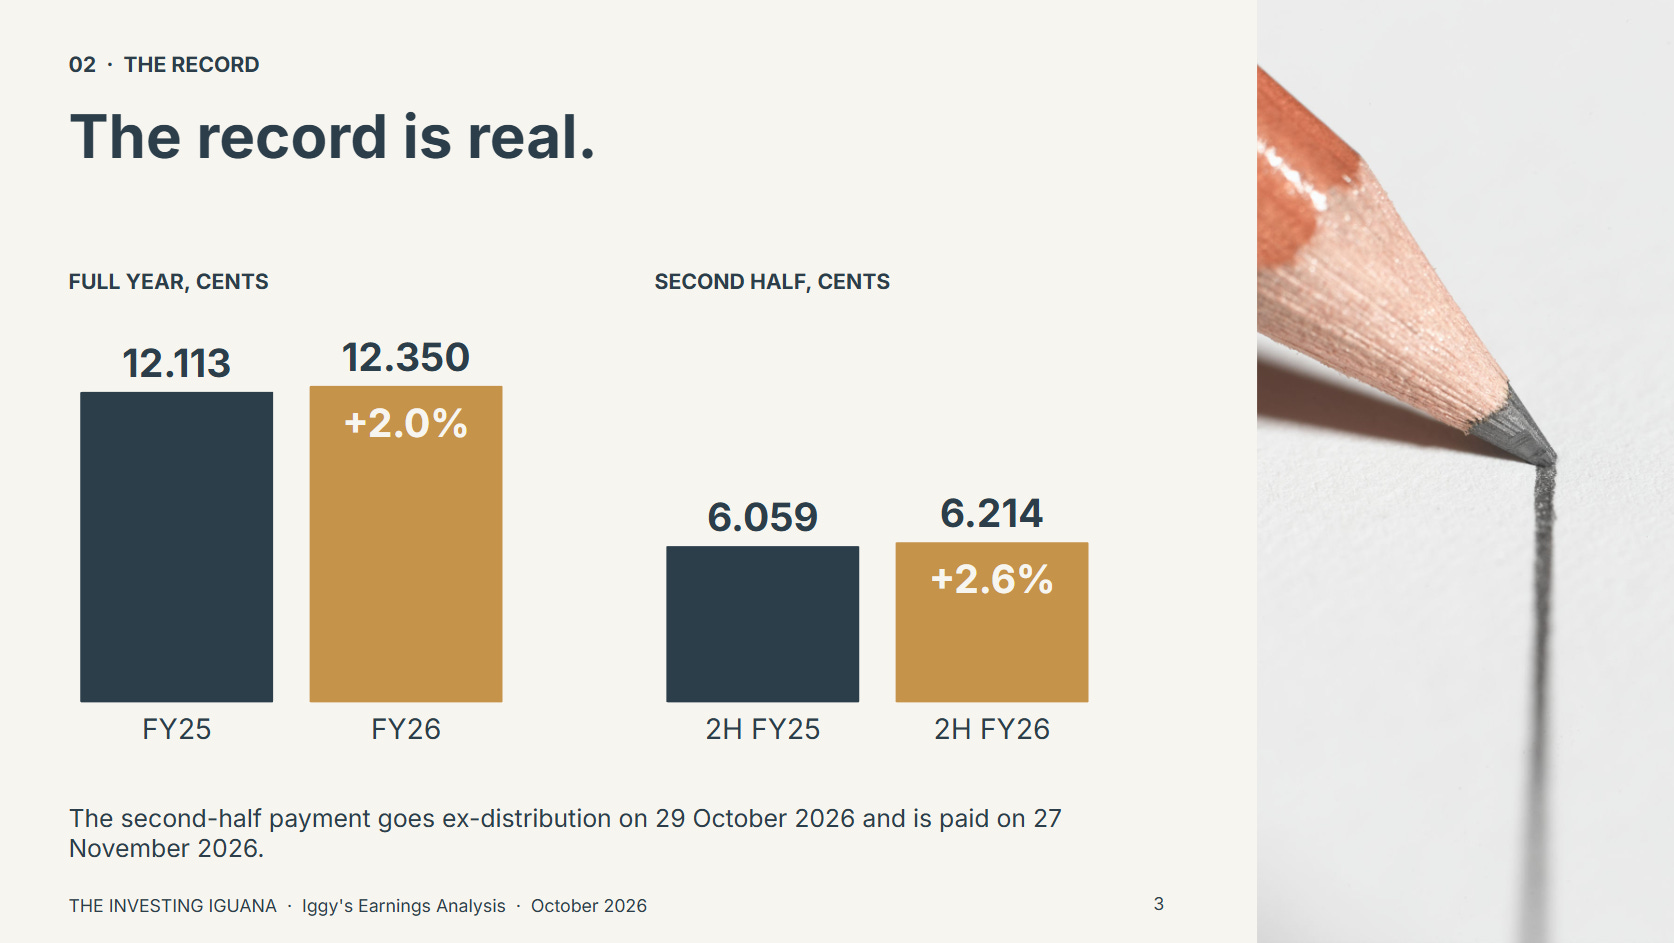
DPU means distribution per unit, the cash FCT pays for each unit you hold. For the full year it came to 12.350 cents, up 2.0% from 12.113 cents. For the second half alone it was 6.214 cents, up 2.6% from 6.059 cents. The second-half payment goes ex-distribution on 29 October 2026 and is paid on 27 November 2026.
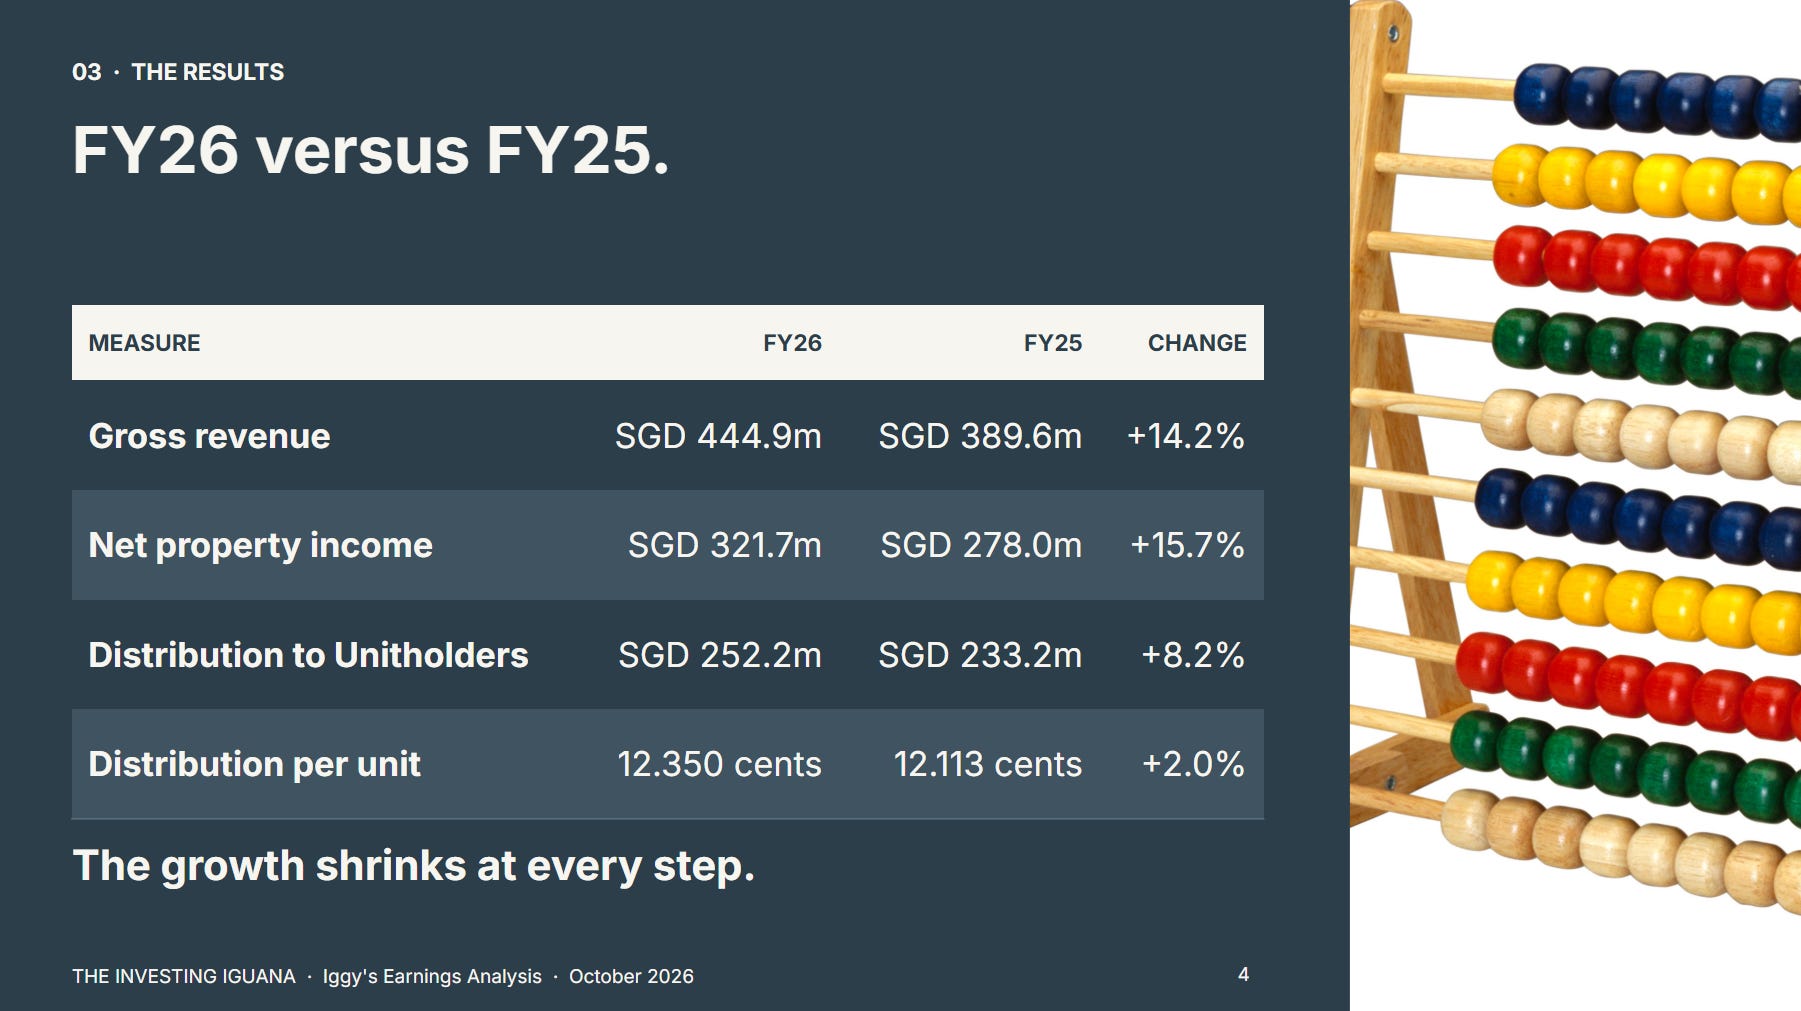
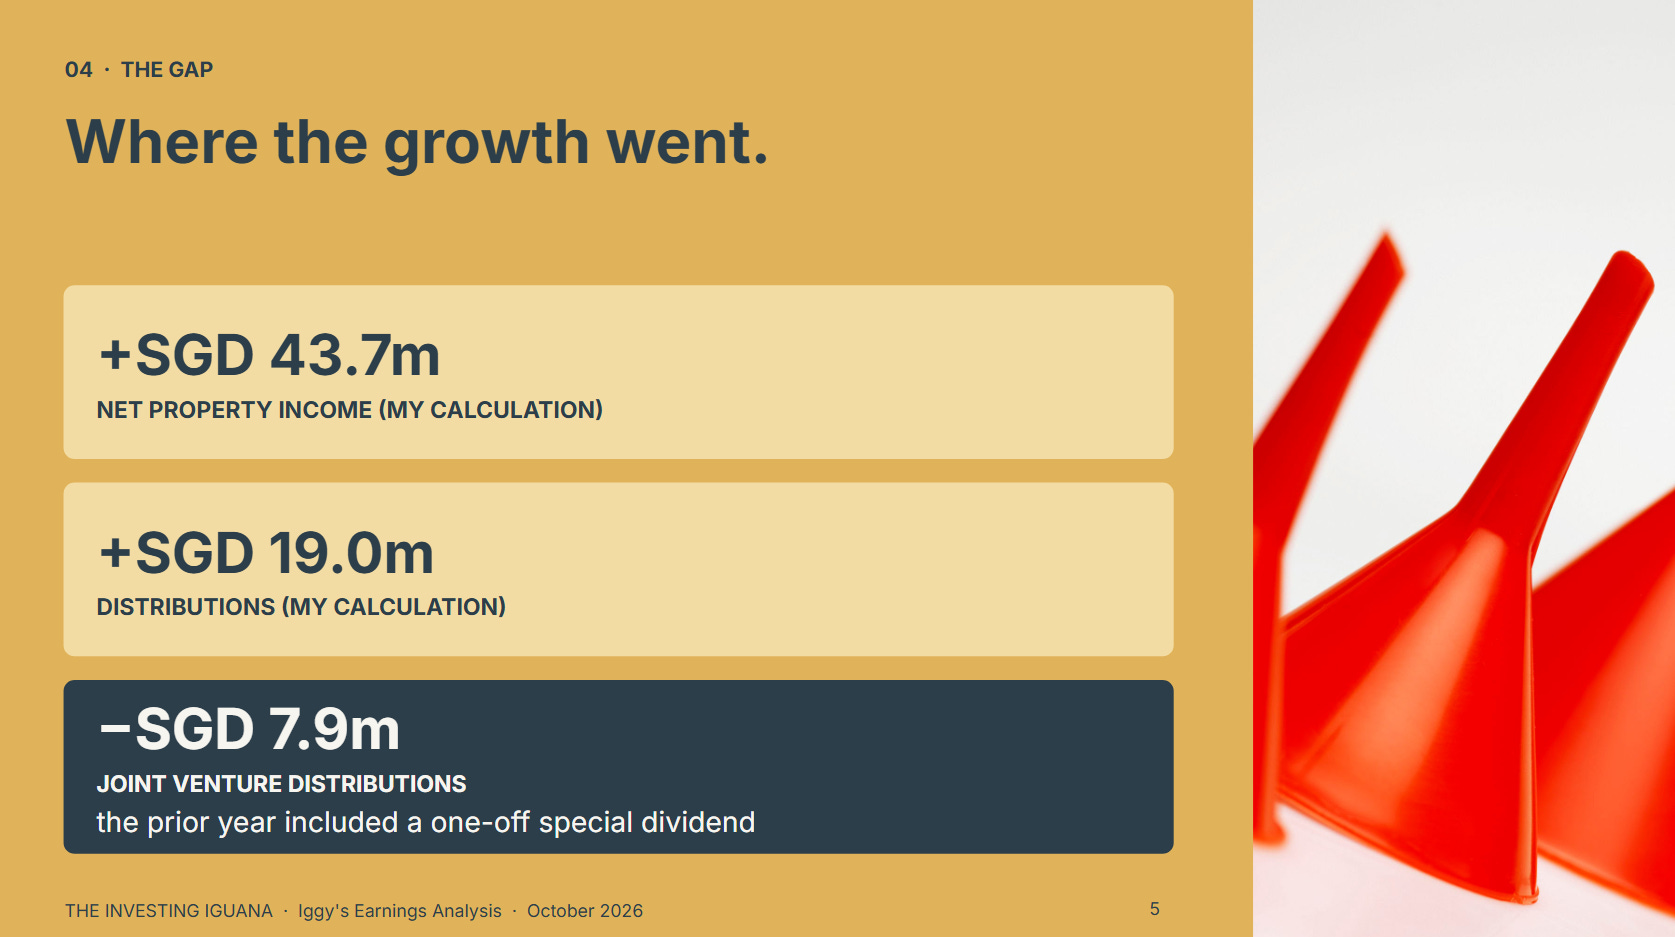
Read down the table and the growth shrinks at every step. NPI rose SGD 43.7m and distributions rose SGD 19.0m, both my own arithmetic. The deck explains the top of the table: Northpoint City South Wing, bought in May 2025, contributed a full year this time against about four months in FY25, and passing rents rose across most malls. Distributions from joint ventures fell 11.7% to SGD 59.6m, SGD 7.9m lower, because the prior year included a one-off special dividend. That accounts for part of the shrinkage. I did not find the finance cost line in the presentation, so I cannot show how much of the rest went to interest.
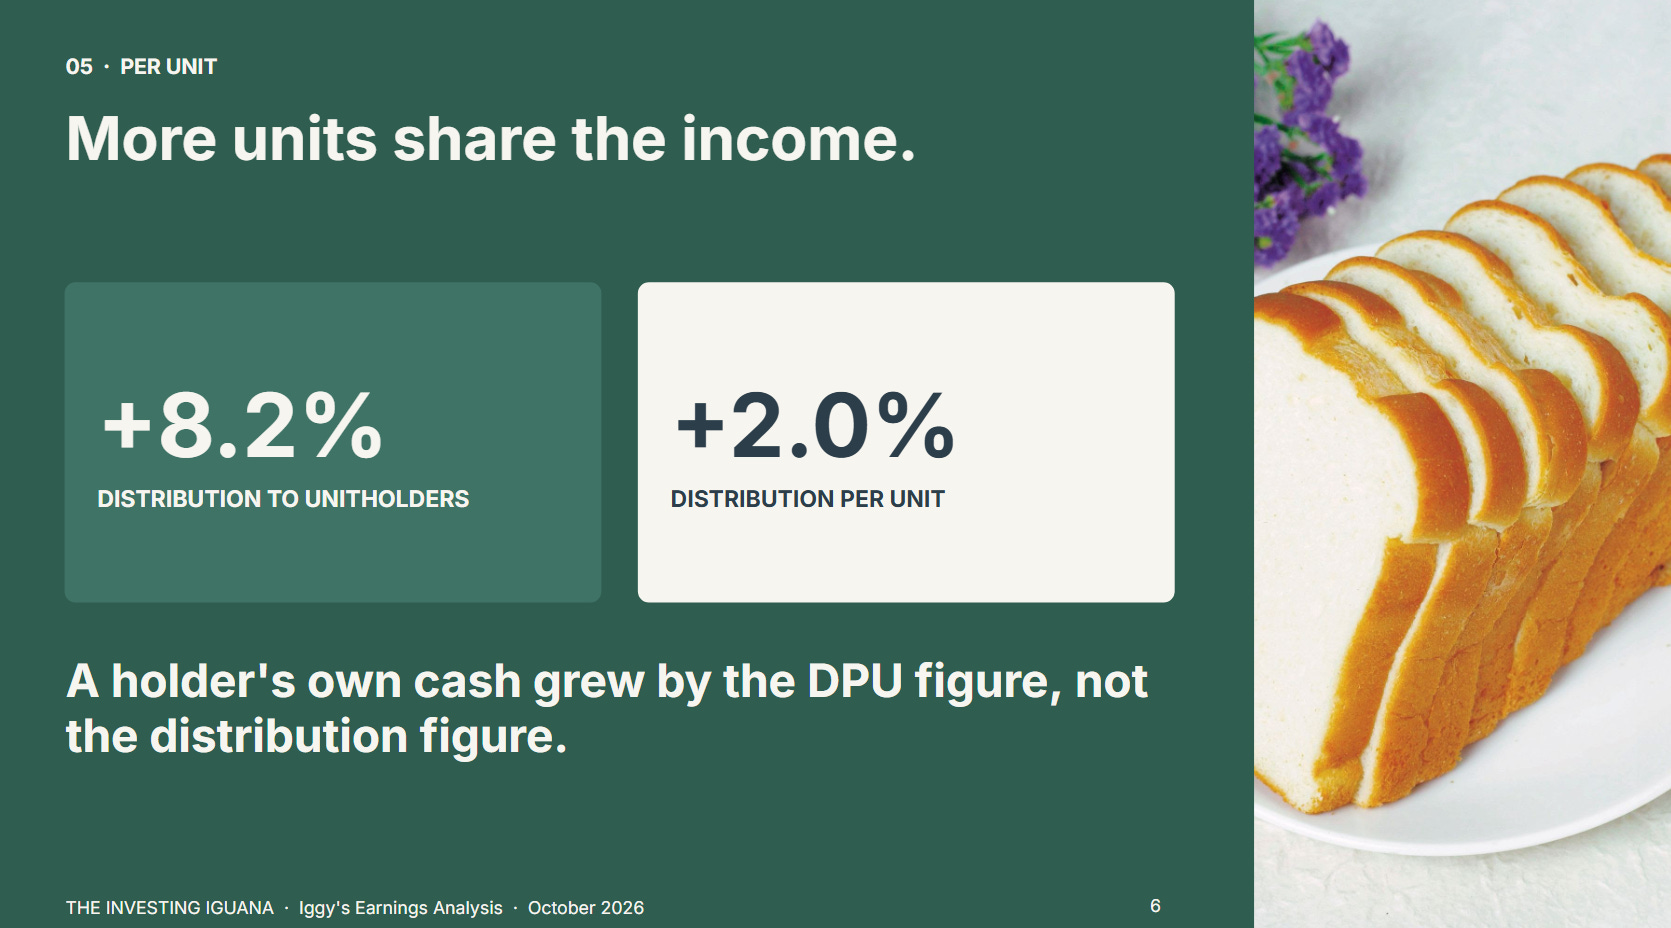
The step from 8.2% to 2.0% means more units now share the income. A property bought partly with new units would produce exactly this. I did not find the unit count or the South Wing funding mix in the presentation, so I will not put a number on it. What I can say is that a holder’s own cash grew by the DPU figure, not the distribution figure.
The pushback I expect is fair: a record payout, 99.7% occupied malls and a 5.78% yield, so what more do you want? The yield and the occupancy clear my gates. One gate does not. I get to it below.
Is the growth coming from the malls?
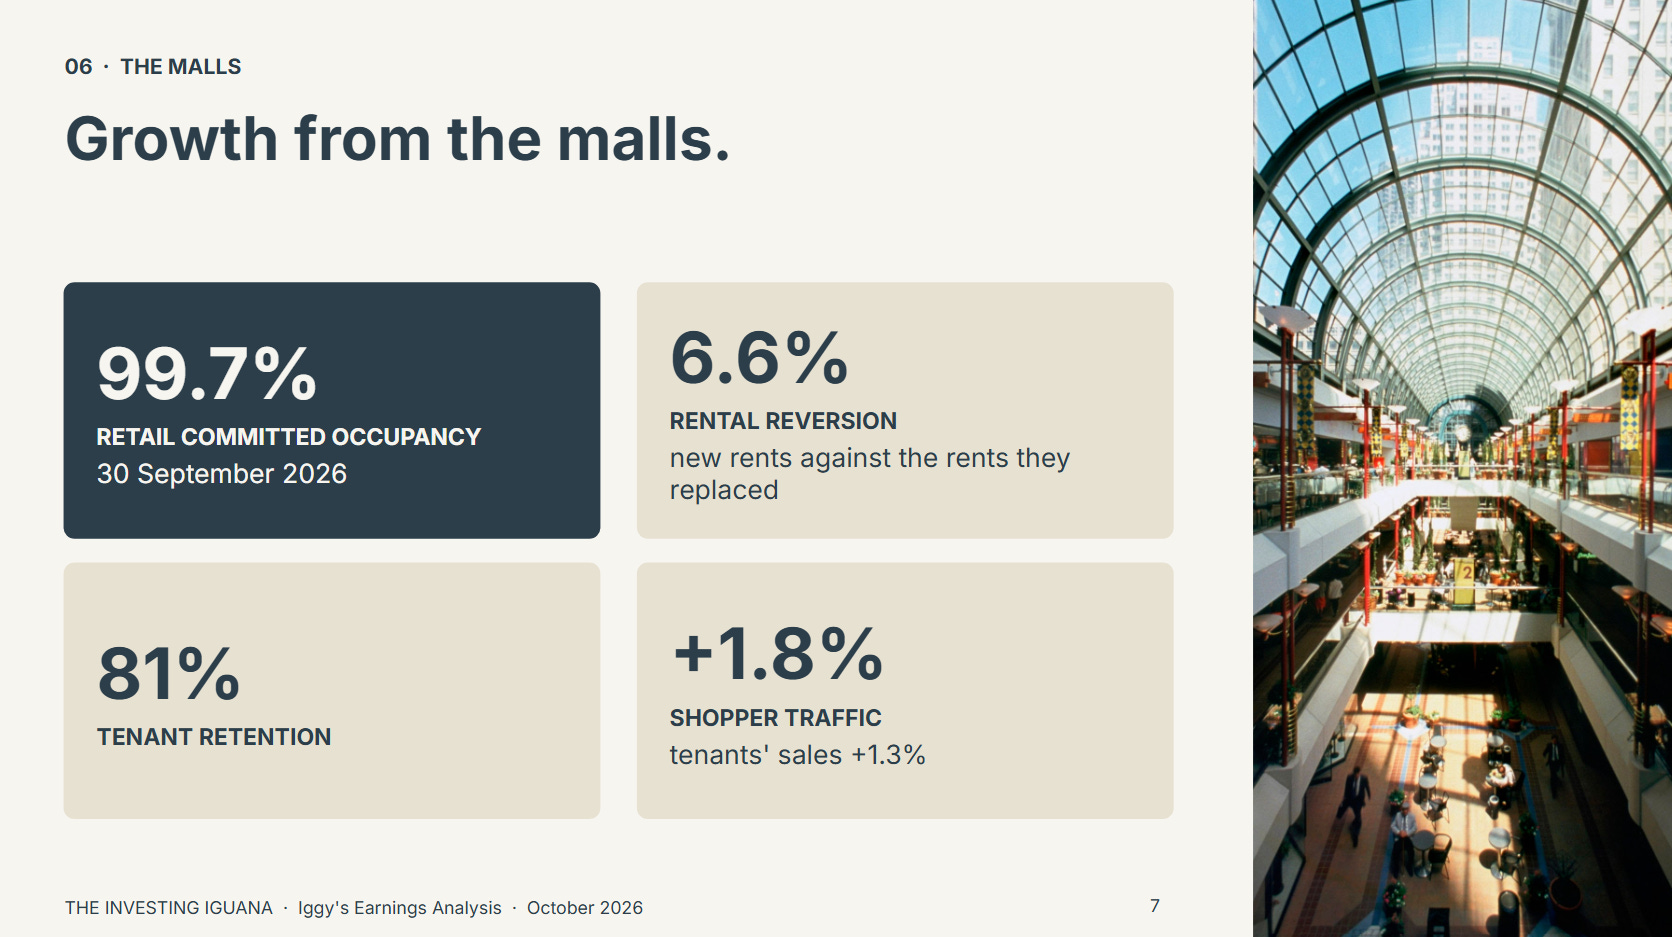
Mostly yes. The deck shows every mall with higher revenue and NPI in FY26. Retail committed occupancy is 99.7% at 30 September 2026, rental reversion for the year is 6.6% (new rents set against the rents they replaced), and tenant retention is 81%. Shopper traffic rose 1.8% in the year and tenants’ sales rose 1.3%.
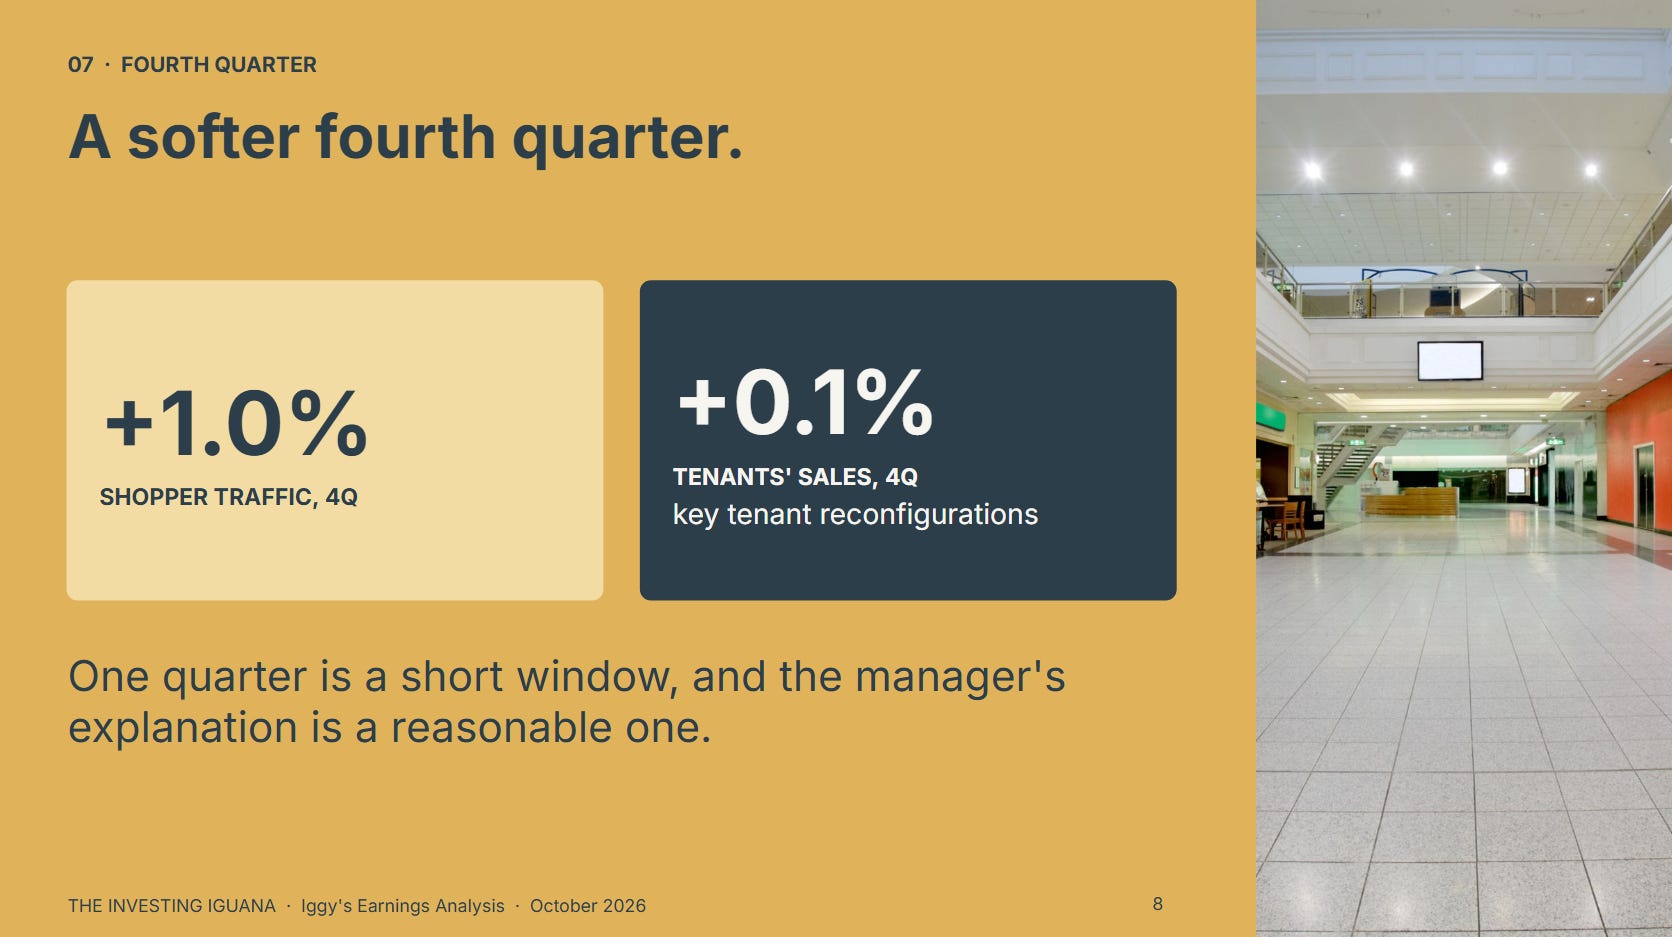
The fourth quarter is a softer picture. Traffic rose 1.0% and tenants’ sales rose only 0.1%, which the manager attributes to key tenant reconfigurations. One quarter is a short window, and the manager’s explanation is a reasonable one. It is also the number I would watch in the first half of FY27. The manager says occupancy cost, the share of a tenant’s sales paid out as rent, has stayed stable around 16%.
What is being rebuilt?
Three malls are in asset enhancement work, which means rebuilding space while the mall keeps trading. Hougang Mall finished, with about 8% return on a SGD 47.0m spend and 49 new-to-mall concepts. NEX Phase 1 completes in December 2026 and is 98% pre-committed, and Phase 2 starts in January 2027 on a SGD 90m budget shared equally with joint venture partners, targeting about 7%. Causeway Point is scheduled from the second quarter of 2027 to the second quarter of 2029.
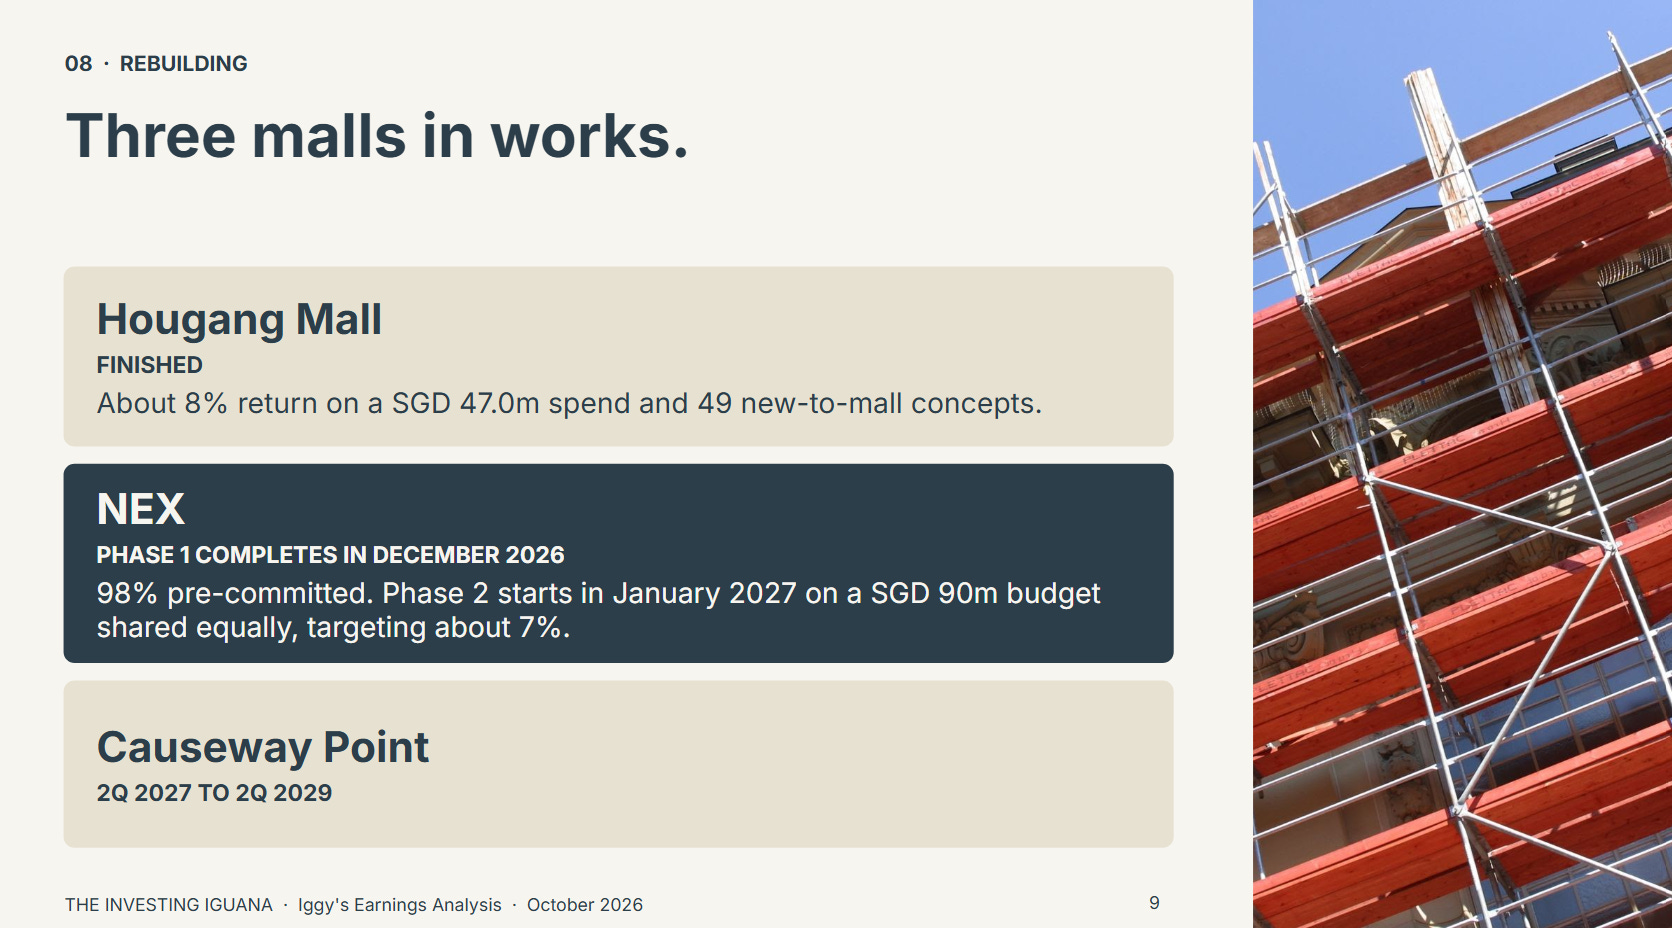
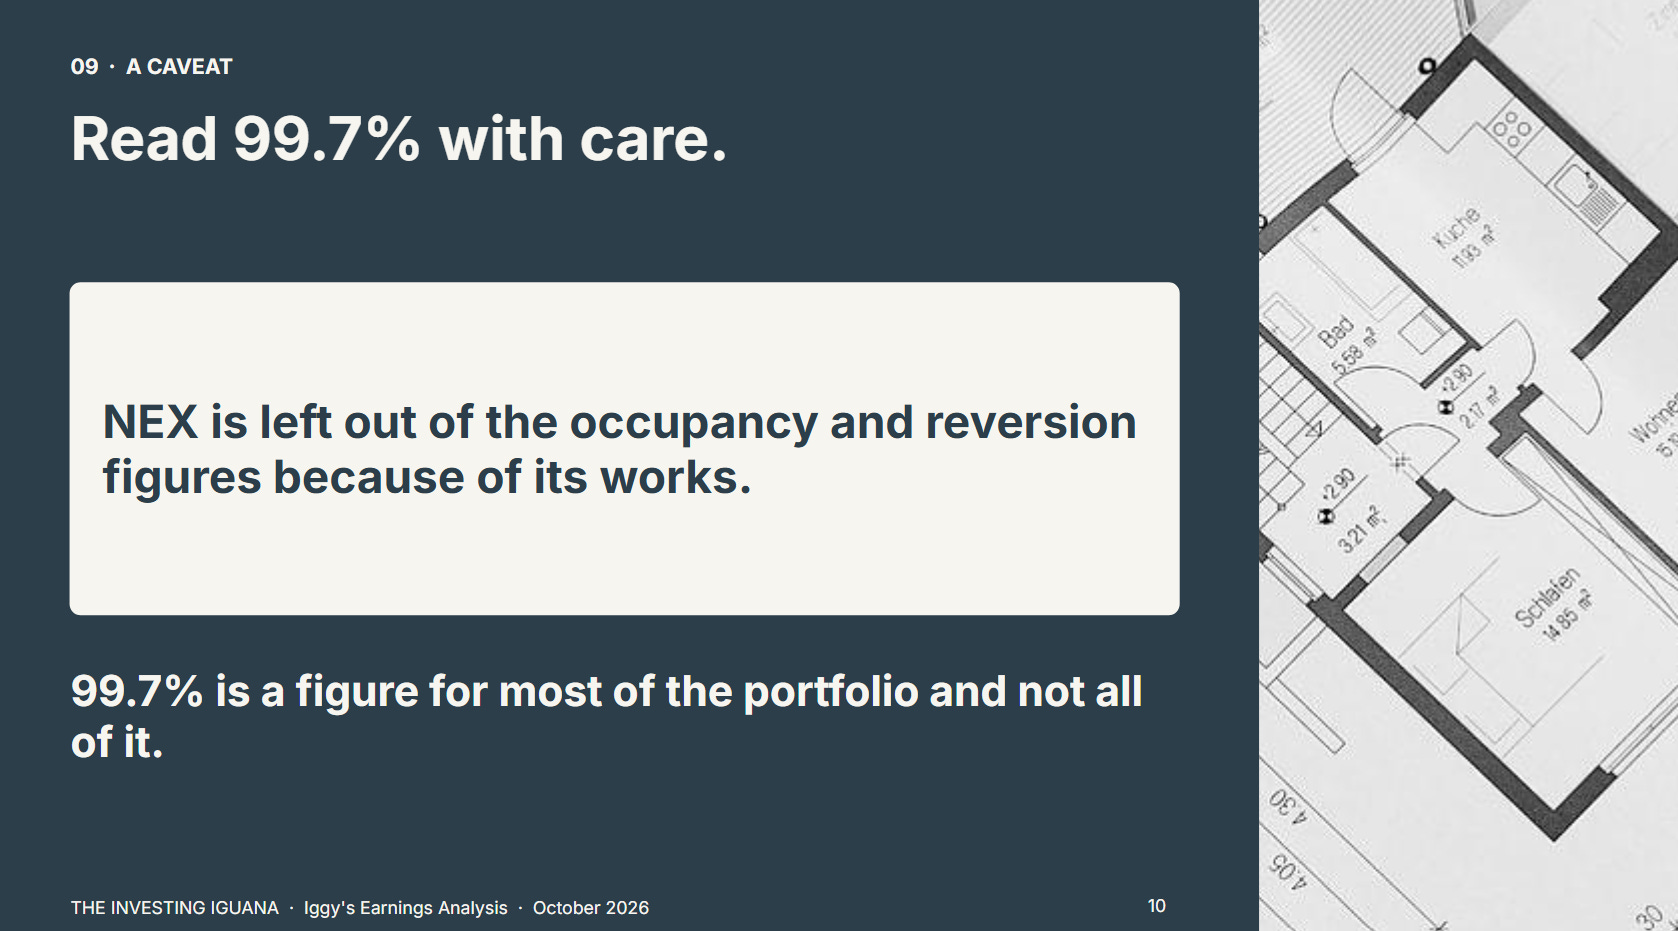
Rebuilding earns the return later and costs some income in the meantime. NEX is already left out of the occupancy and reversion statistics because of its works, so the cleanest-looking numbers in the deck come from the malls that are not being rebuilt. That is a normal way to report. It is also a reason to read 99.7% as a figure for most of the portfolio and not all of it.
Dividend Trajectory
Before the zone, one check on how large the record really is.
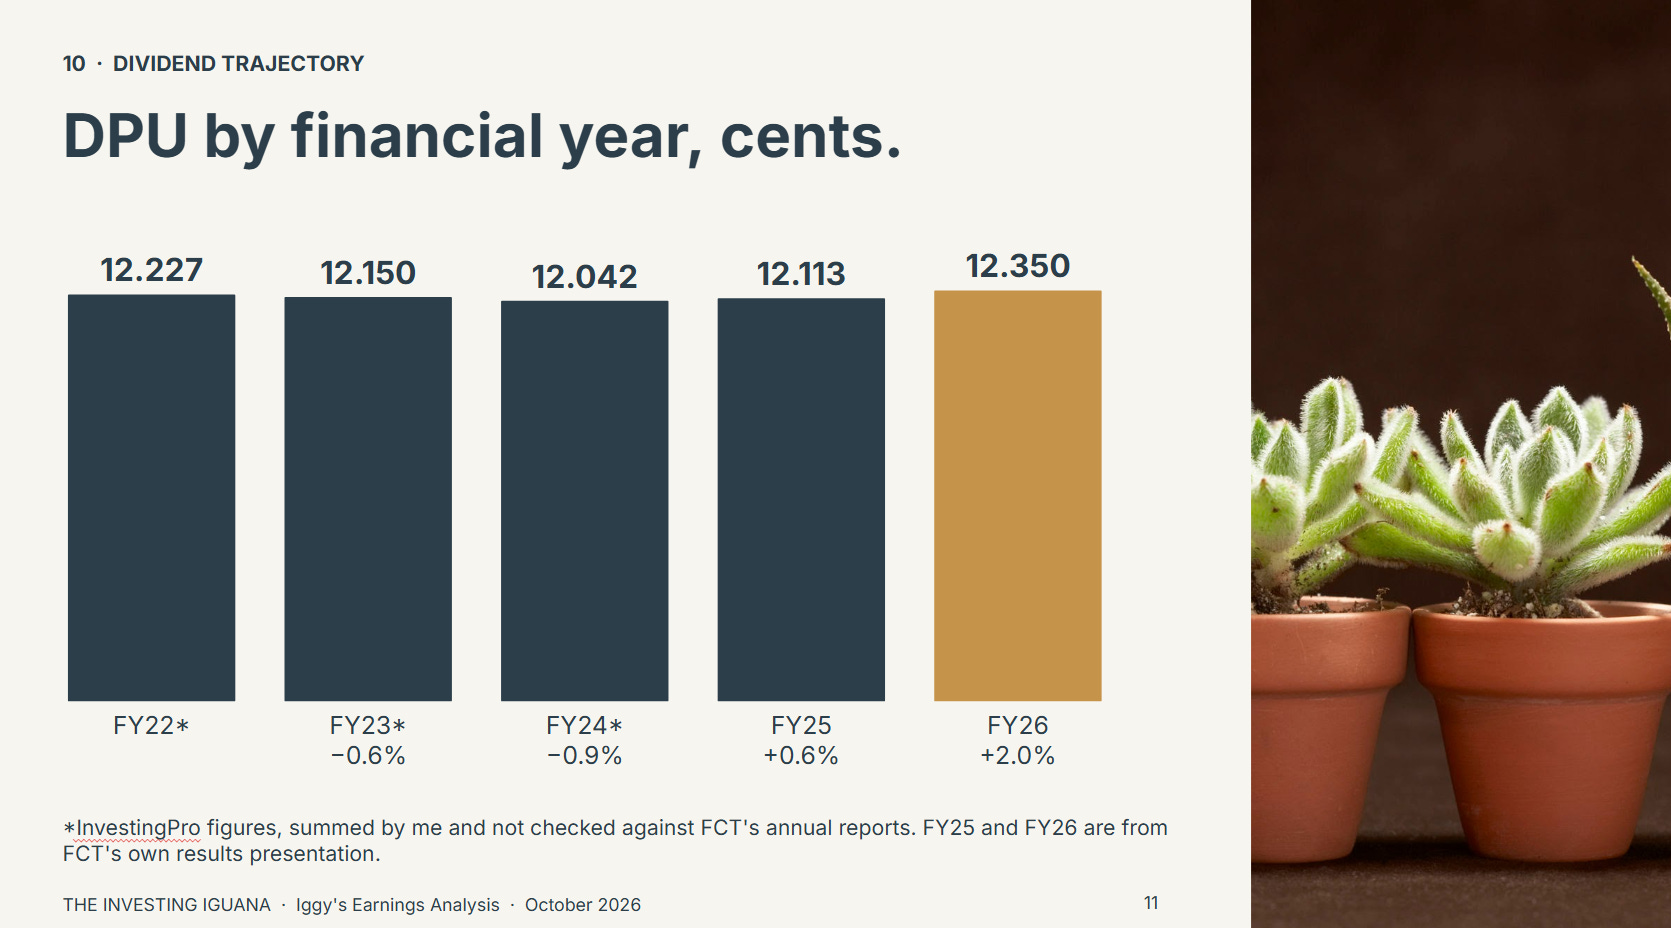
*From InvestingPro’s dividend history, summed by me, and not checked against FCT’s annual reports. FY25 and FY26 are from FCT’s own results presentation. For FY25 the vendor’s total matches the company’s.
🦎Iggy’s Insights
FY26’s 12.350 cents is a record. It is also 1.0% above FY22’s 12.227 cents, which is four years of rent increases, an acquisition and three malls under asset enhancement producing one percent more cash per unit. The record is real, and it is also small. Income investors should read the direction of the next three payments, not the label on this one. If each of the next three payments rises by even 2%, the four-year picture changes. If they do not, the record stands as a one-year high on a flat base.
Valuation Table
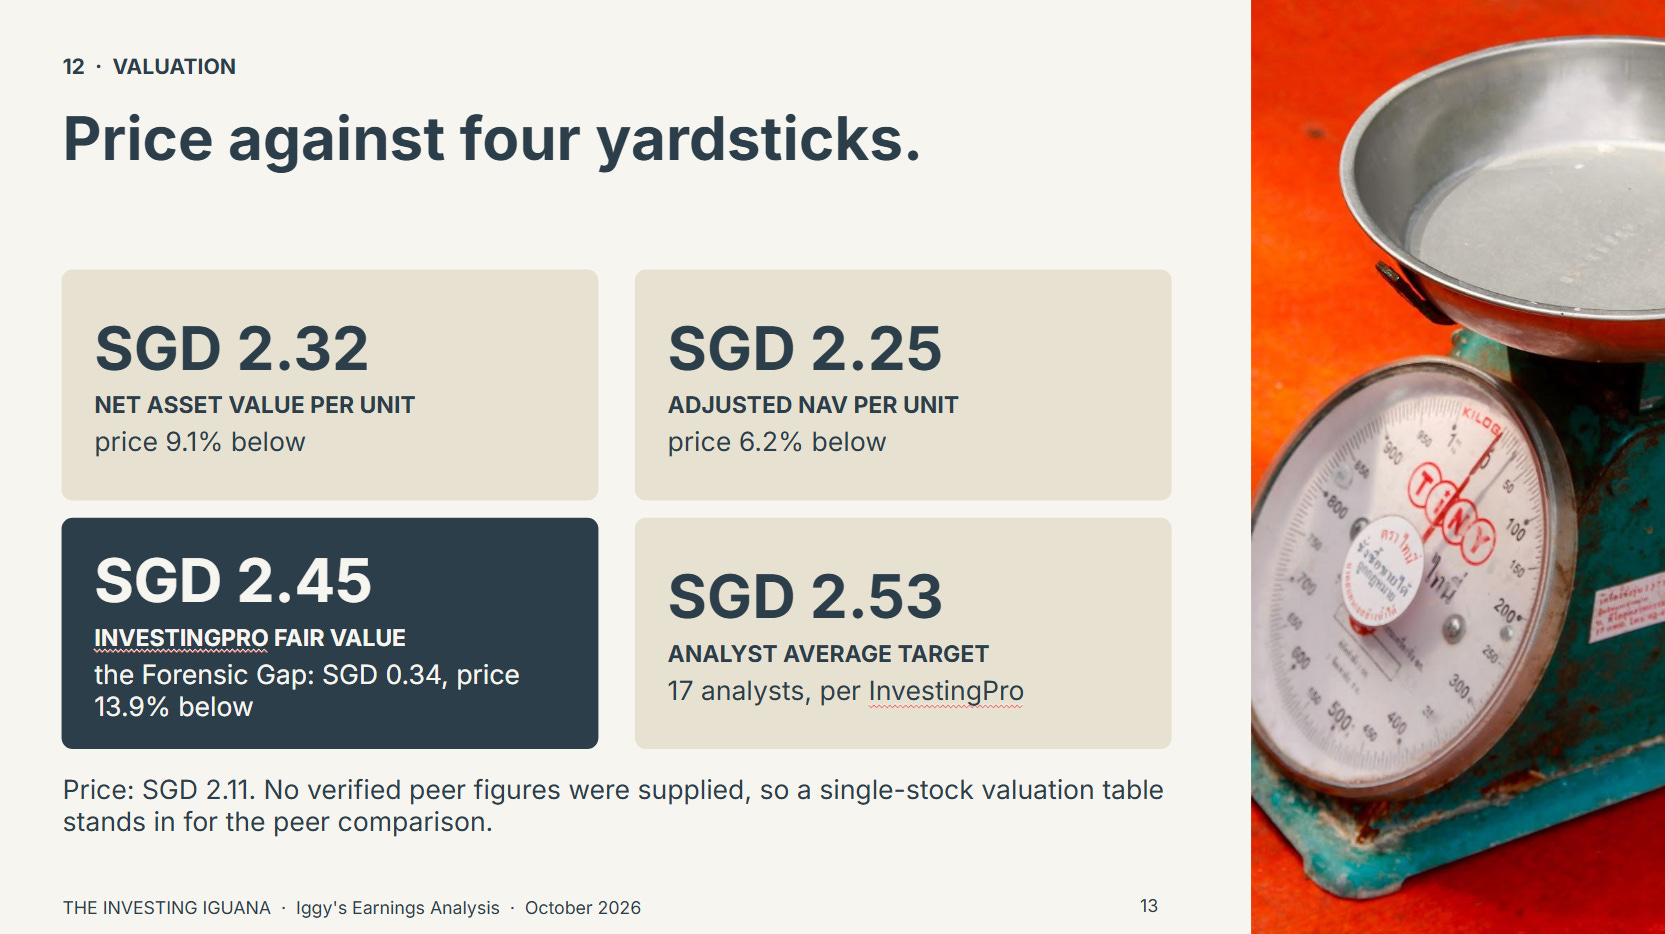
I have no verified peer figures for this piece, so I have used a single-stock valuation table in place of the peer comparison. The Forensic Gap does not change the zone, because the zone rests on the gates and the gearing gate fails regardless of price.
That is the earnings picture. Now the screen.
Where FCT Sits on My Screen
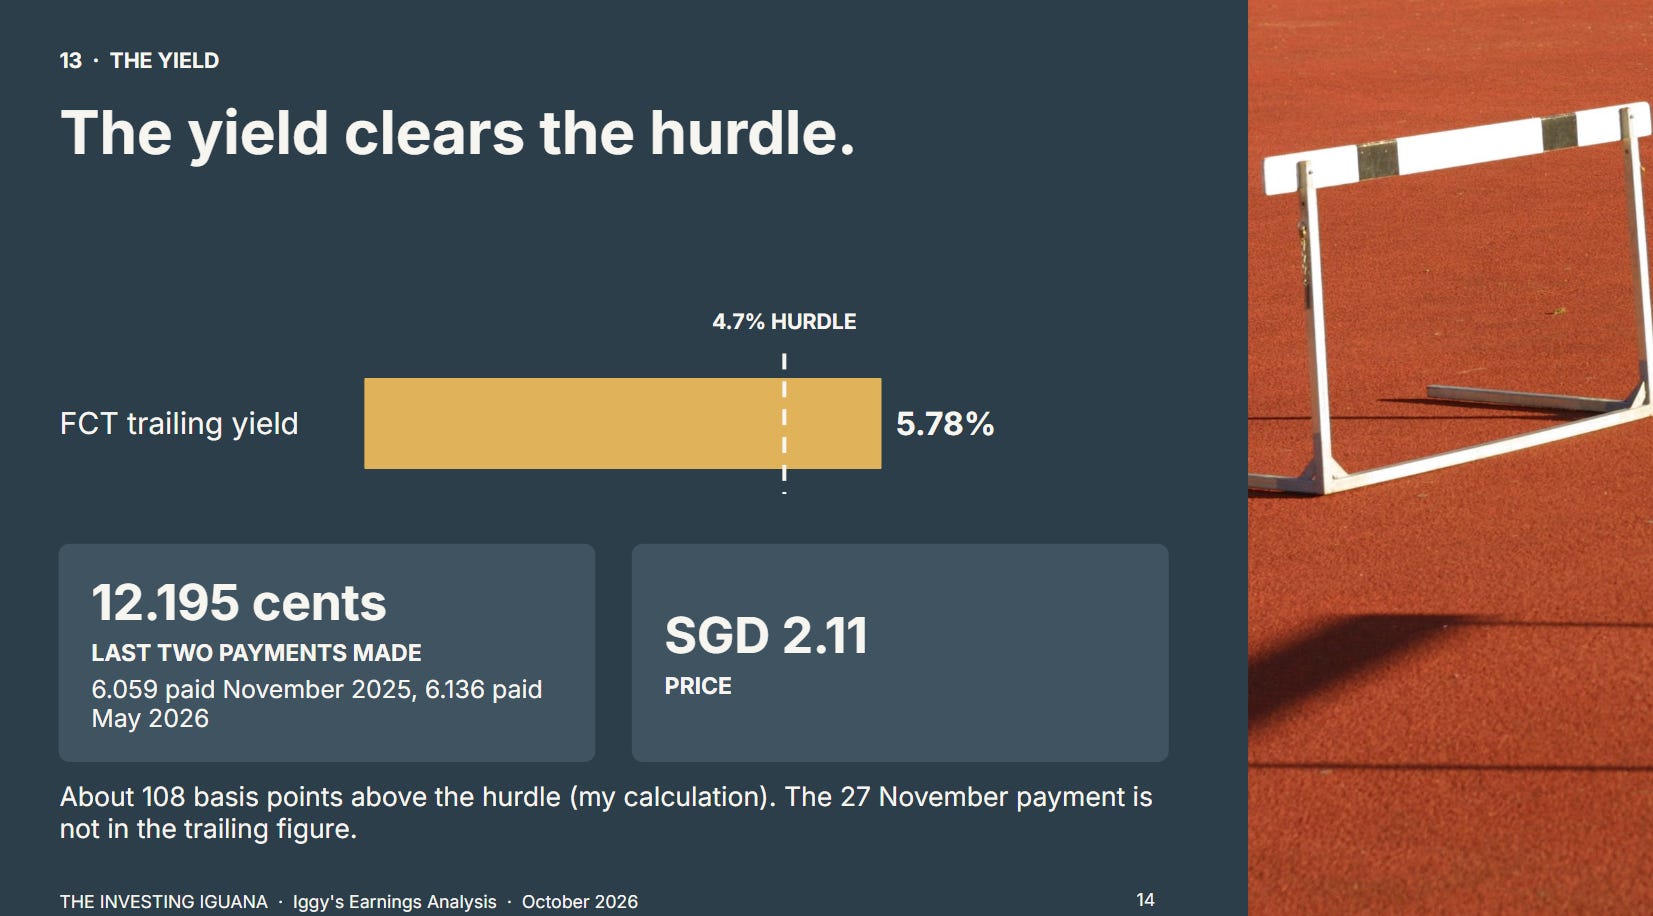
At SGD 2.11, the trailing yield on the last two half-year payments actually made is 5.78%. That is 12.195 cents (6.059 paid in November 2025 plus 6.136 paid in May 2026) over the price. The second-half payment due on 27 November has not been paid yet, so it is not in the trailing figure. The yield clears my 4.7% hurdle by about 108 basis points, so the yield is not the constraint.
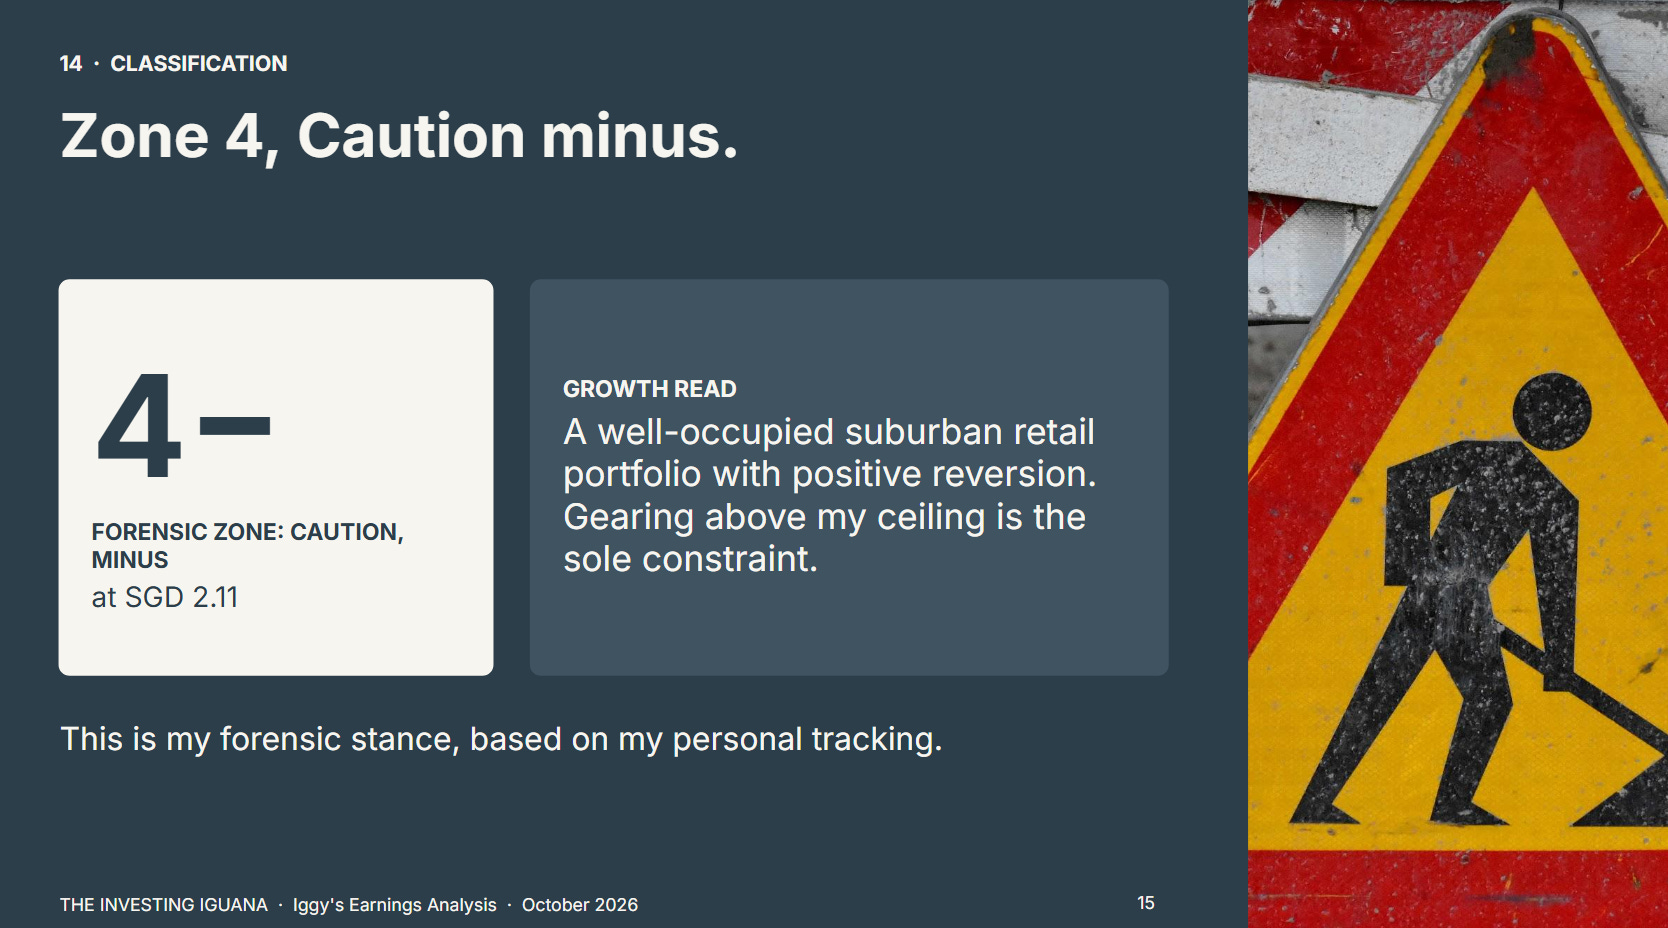
Iggy’s Forensic Zone: Zone 4, Caution - (Growth Read: a well-occupied suburban retail portfolio with positive reversion, gearing above my ceiling is the sole constraint)
The members’ half shows exactly which gate carries the verdict, how far over it is, what the suffix means, and what would change it.
What the Paid Half Adds
The free half covers the results. The paid half is the audit: how far gearing sits above my ceiling and why that earns a minus, whether the White Sands repayment actually gets gearing to 36.8% and what is still missing after it, how much room interest cover has, how much of the debt is fixed, which soft flag applies, and what the result means for a holder from earlier years against fresh capital. The extra is depth, nothing else.
The Substack Only Plan, US$8/month, gives the full written analysis, portfolio walkthroughs and analyst cheatsheets.
The YouTube Only Plan, S$5/month, gives the full-length Members Edition video.
The YouTube/Substack Combo, S$12/month, gives all of it.
🔒 What’s Next
The 38.7% gearing figure has a manager’s estimate of 36.8% beside it, and the gap between them is a repayment that has not yet shown up in a reported number. The next section shows how far that repayment goes and which of my gates it still leaves open.