


Singtel’s Yield Looks Like 4.3%. Strip Out the One-Off Dividend and It’s 3.1%.
UOB Kay Hian still rates Singtel a buy with a $5.50 target, and the balance sheet backs that up, low debt, strong coverage. The yield is the one number that doesn’t clear my bar.
Iggy’s Forensic Zone: Zone 4, Caution+
More than a dozen analysts cover Singtel, with an average target near $5.34 as of mid-September 2026. UOB Kay Hian’s Chong Lee Len has a $5.50 call on the stock with a buy rating attached. None of that changed what my yield test found when I ran the current numbers.
I get why the Singtel bull case is everywhere right now. Nxera is a genuinely interesting story, and the balance sheet backs up almost everything the optimists are saying about it. If you’ve held Singtel for years, this isn’t a piece telling you to sell, your yield on cost from an earlier entry price is a different number entirely from the one I’m about to walk through. If you’re deciding whether today’s price gets you an income holding or a growth bet dressed up as one, that’s the actual question this screen answers.
The Analyst’s Case
Iggy’s Forensic Screen
Financial Health Checklist
The Dividend Trajectory
The Forensic Gap
What’s Next
Insight Callout
What To Watch Next
Insight Callout
Iggy’s Forensic Zone
Legacy Holders vs. Fresh Capital
Iggy’s Elite Read
The Analyst’s Case
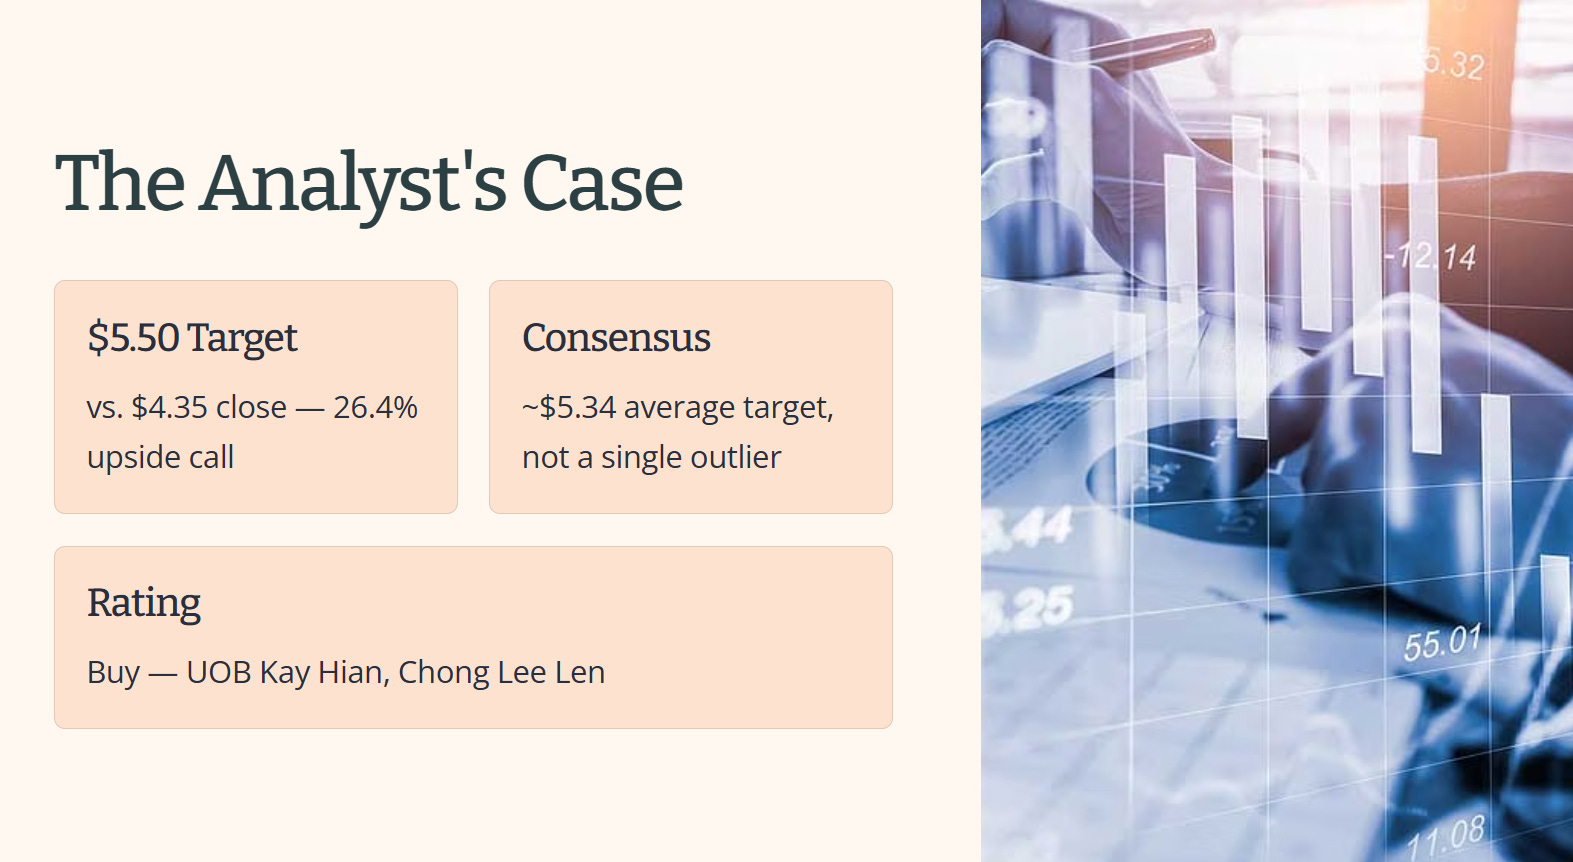
UOB Kay Hian’s Chong Lee Len maintains a buy on Singtel, with a $5.50 target price against a $4.35 close, a 26.4% upside call. He’s not alone. More than a dozen analysts cover the stock and their average target sits near $5.34 as of mid-September 2026, so the bullish read isn’t a single outlier report, it’s close to consensus.
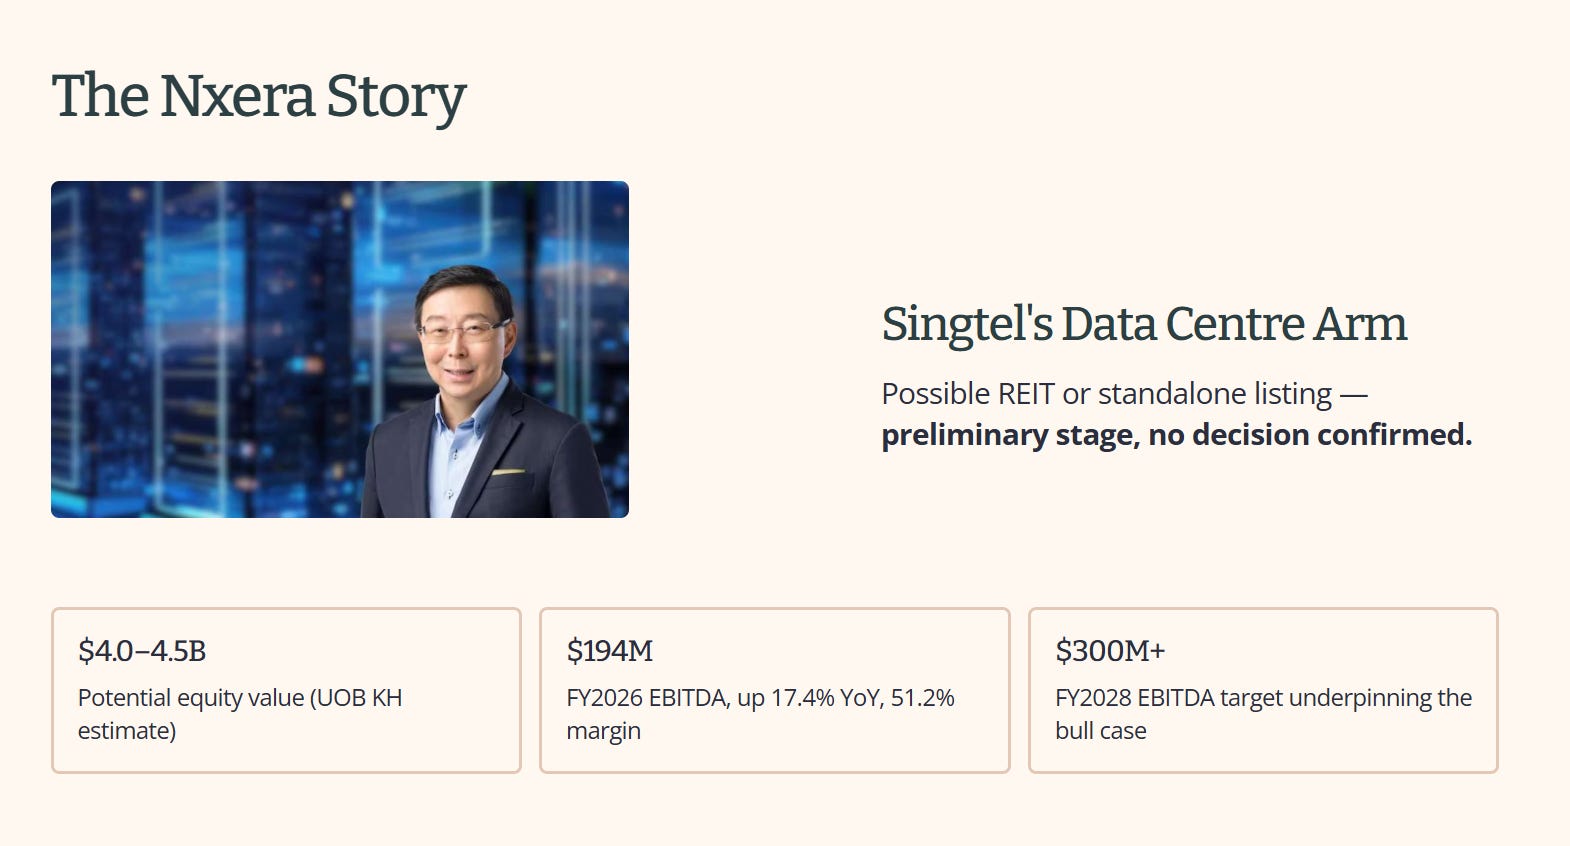
The case leans heavily on Nxera, Singtel’s data centre arm. Management is exploring a possible REIT structure or a standalone listing for the business, still at a preliminary stage with no decision confirmed on scale, date, or structure. UOB Kay Hian’s own estimate puts a potential Nxera equity value at $4.0 billion to $4.5 billion if a transaction goes ahead, built on projected FY2028 EBITDA above $300 million. Nxera’s FY2026 numbers back up the growth story on its own terms, segment EBITDA came in at $194 million (per Singtel’s FY2026 Group MD&A, SGX filing), up 17.4% year on year, with a 51.2% margin.
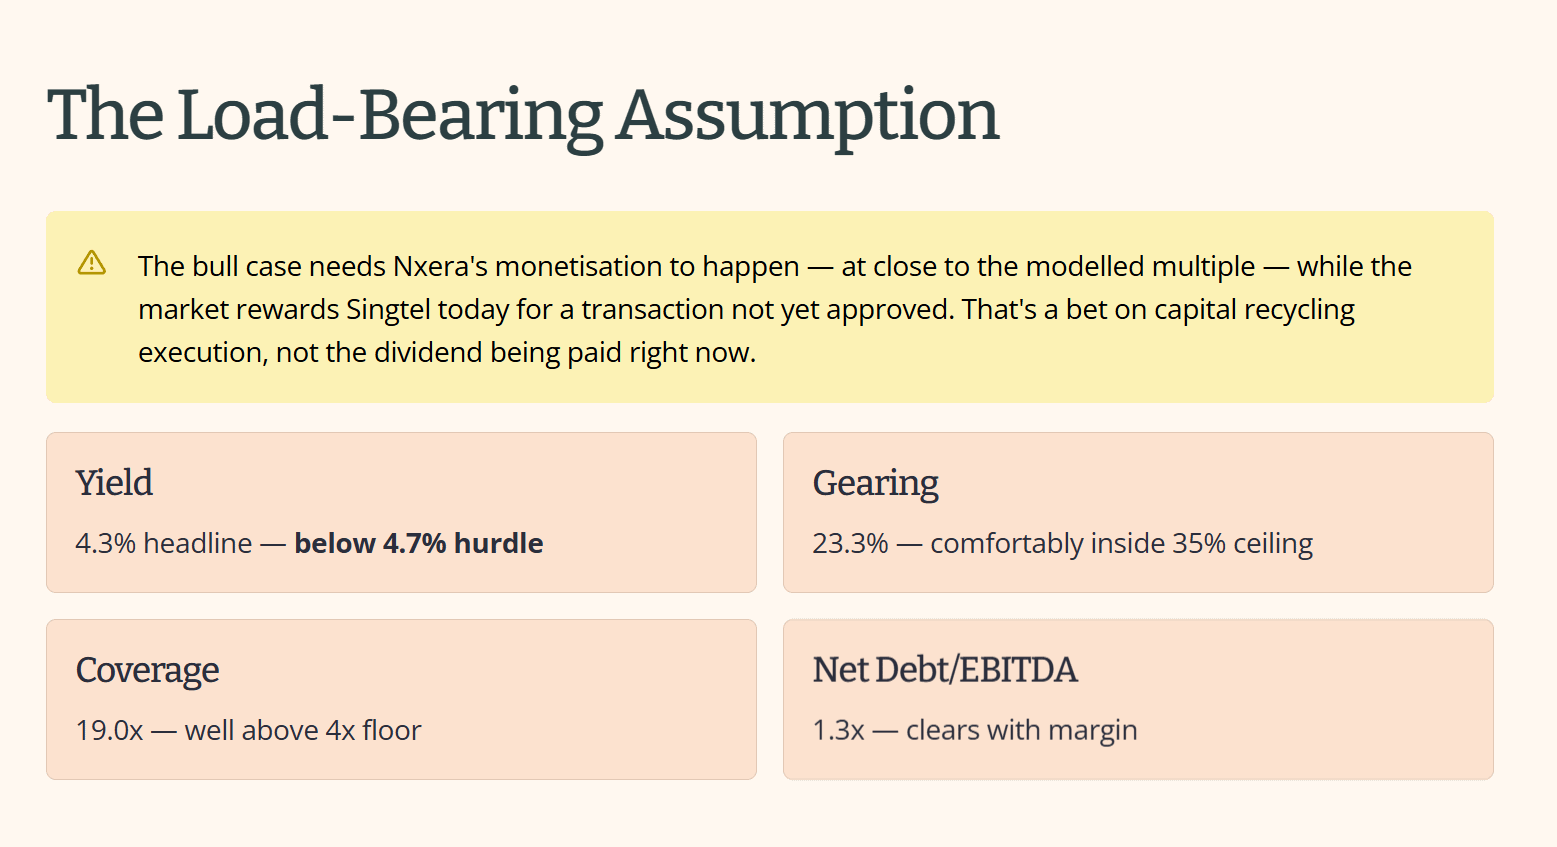
THE LOAD-BEARING ASSUMPTION: strip away the target price and what the bull case actually needs is for Nxera’s monetisation to happen, and to happen at something close to the multiple UOB Kay Hian has modelled, while the market keeps rewarding Singtel today for a transaction that hasn’t been approved yet. That’s a bet on capital recycling execution and re-rating, not a read on the dividend Singtel is paying out right now.
That’s the bull case on its own terms. Here’s what happens when I run Singtel through my own forensic screen instead of taking the target price at face value.
Iggy’s Forensic Screen
Layer one, the raw facts. Singtel’s headline trailing dividend yield is 4.3%, below my 4.7% minimum hurdle. Gearing, the share of the balance sheet funded by net debt rather than equity, sits at 23.3%, comfortably inside my 35% ceiling. Interest coverage, how many times over Singtel’s earnings could pay its interest bill, comes in at 19.0x against a 4x floor. Net debt to EBITDA is 1.3x. Every hard gate except yield clears with real margin, most of them by a wide one.
Financial Health Checklist
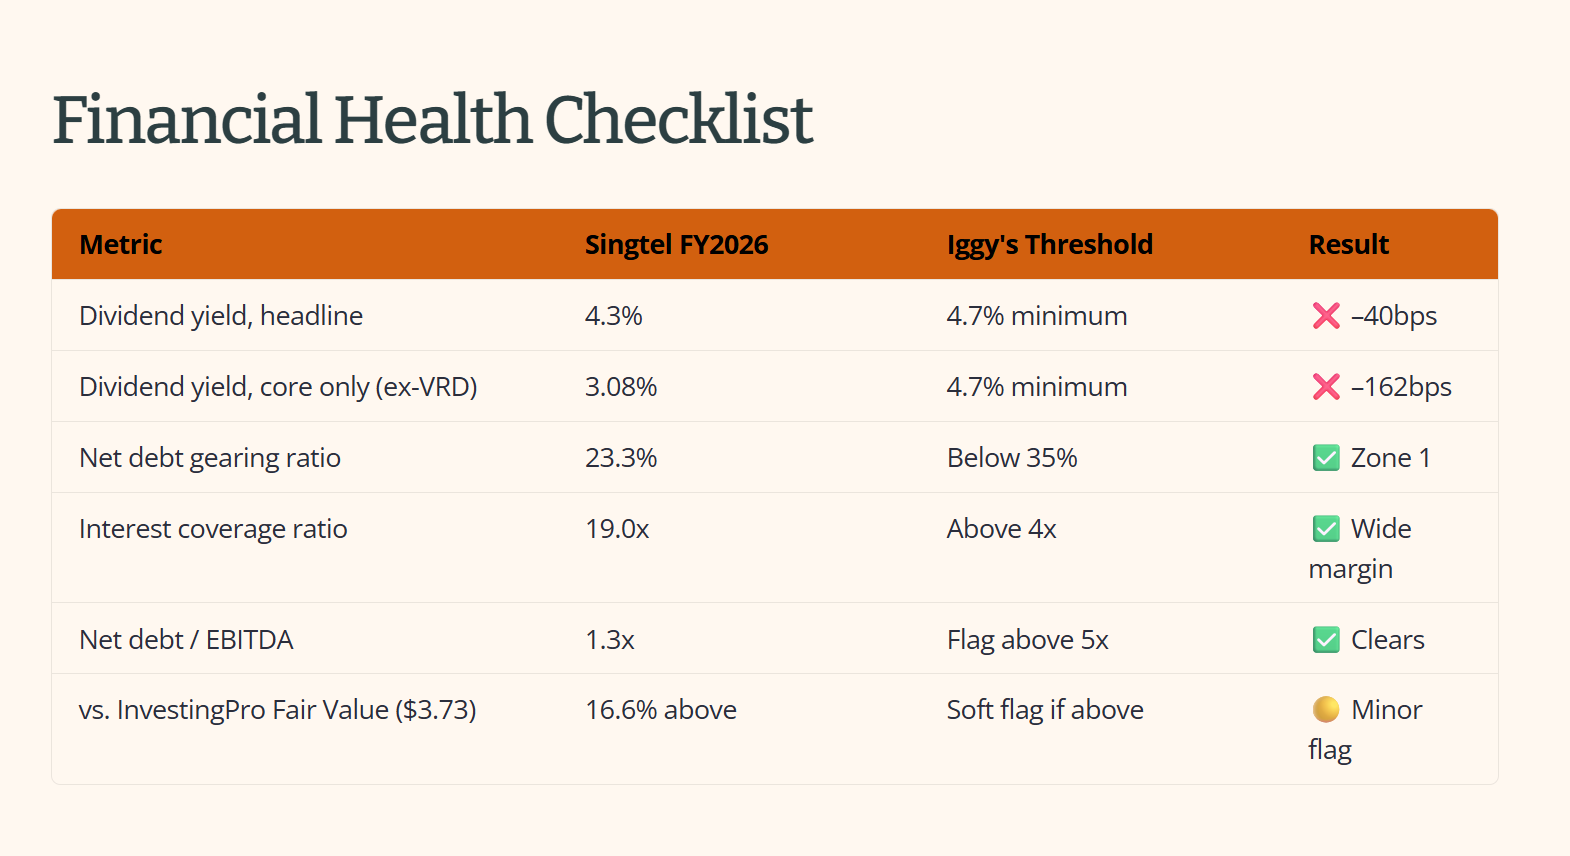
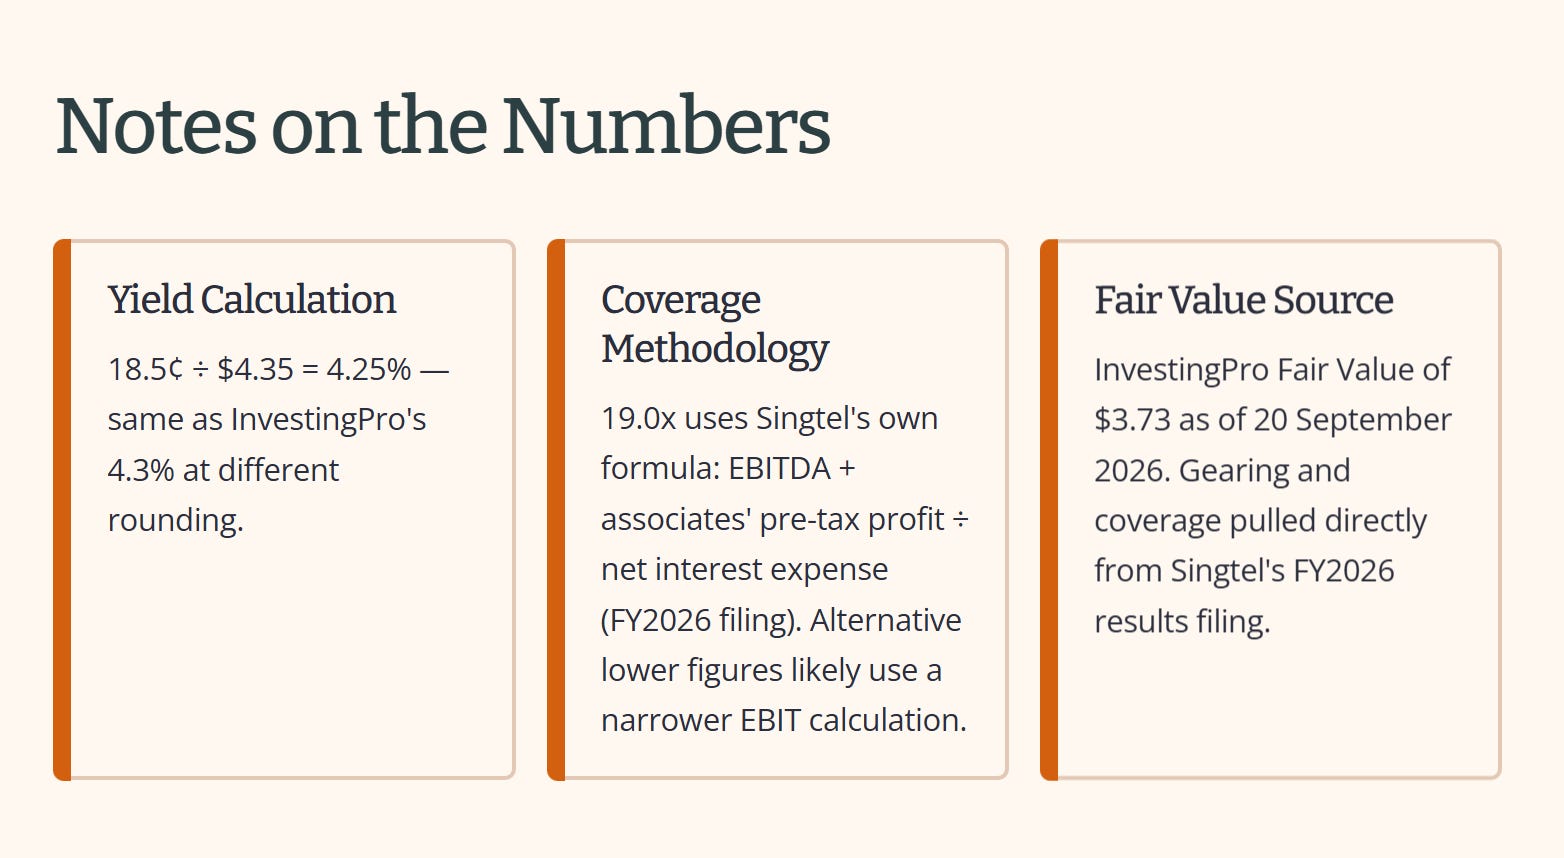
Notes on the table above. InvestingPro’s published trailing yield of 4.3% and the direct calculation from FY2026’s disclosed 18.5 cent total distribution ($18.5 cents / $4.35 = 4.25%) are the same figure at different rounding, used interchangeably here. Interest coverage of 19.0x uses Singtel’s own stated formula, EBITDA plus share of associates’ pre-tax profit, divided by net interest expense, per its FY2026 results filing. A separate publication cites a materially lower figure, most likely using a narrower EBIT-over-gross-interest calculation.
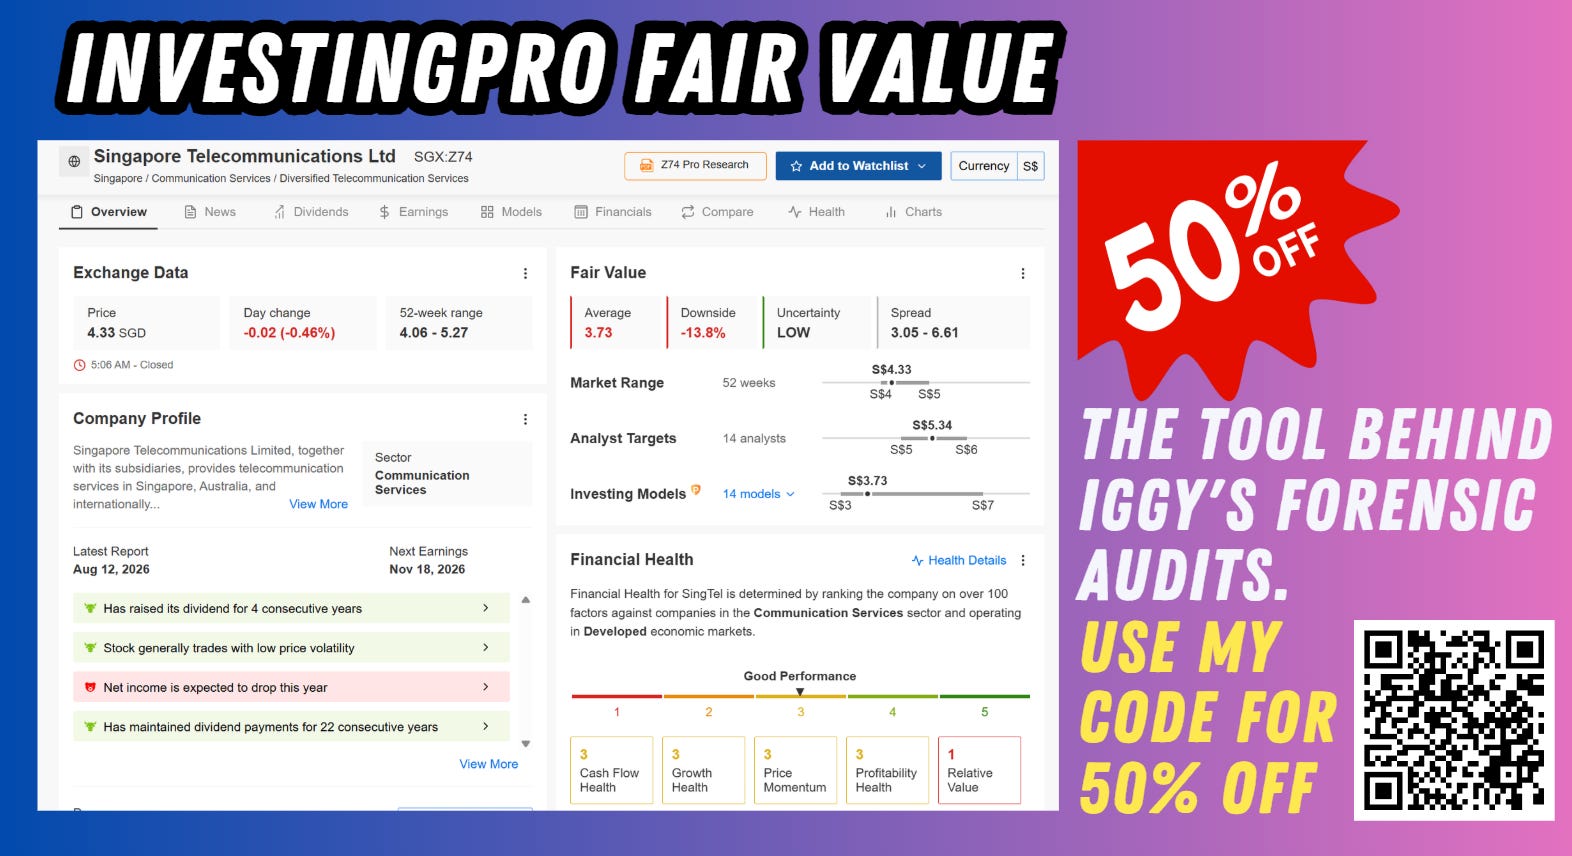
Until that source’s methodology is confirmed, 19.0x stands as the primary-filing figure with a disclosed formula behind it. The InvestingPro Fair Value of $3.73 is per InvestingPro, as of 20 September 2026. Gearing and interest coverage are pulled from Singtel’s own FY2026 results filing directly, InvestingPro’s own gearing and coverage fields weren’t independently visible in what I could retrieve, flagged here for anyone cross-checking against a live terminal before this goes further.
Layer three, peer context. StarHub is the closest SGX telco comparison, and it clears the yield hurdle on InvestingPro’s 5.7% figure. But StarHub’s visible balance sheet inputs imply leverage several multiples higher than Singtel’s, and it has no comparable regional platform or data centre growth arm. It’s a lens on income, not a clean read on business quality.
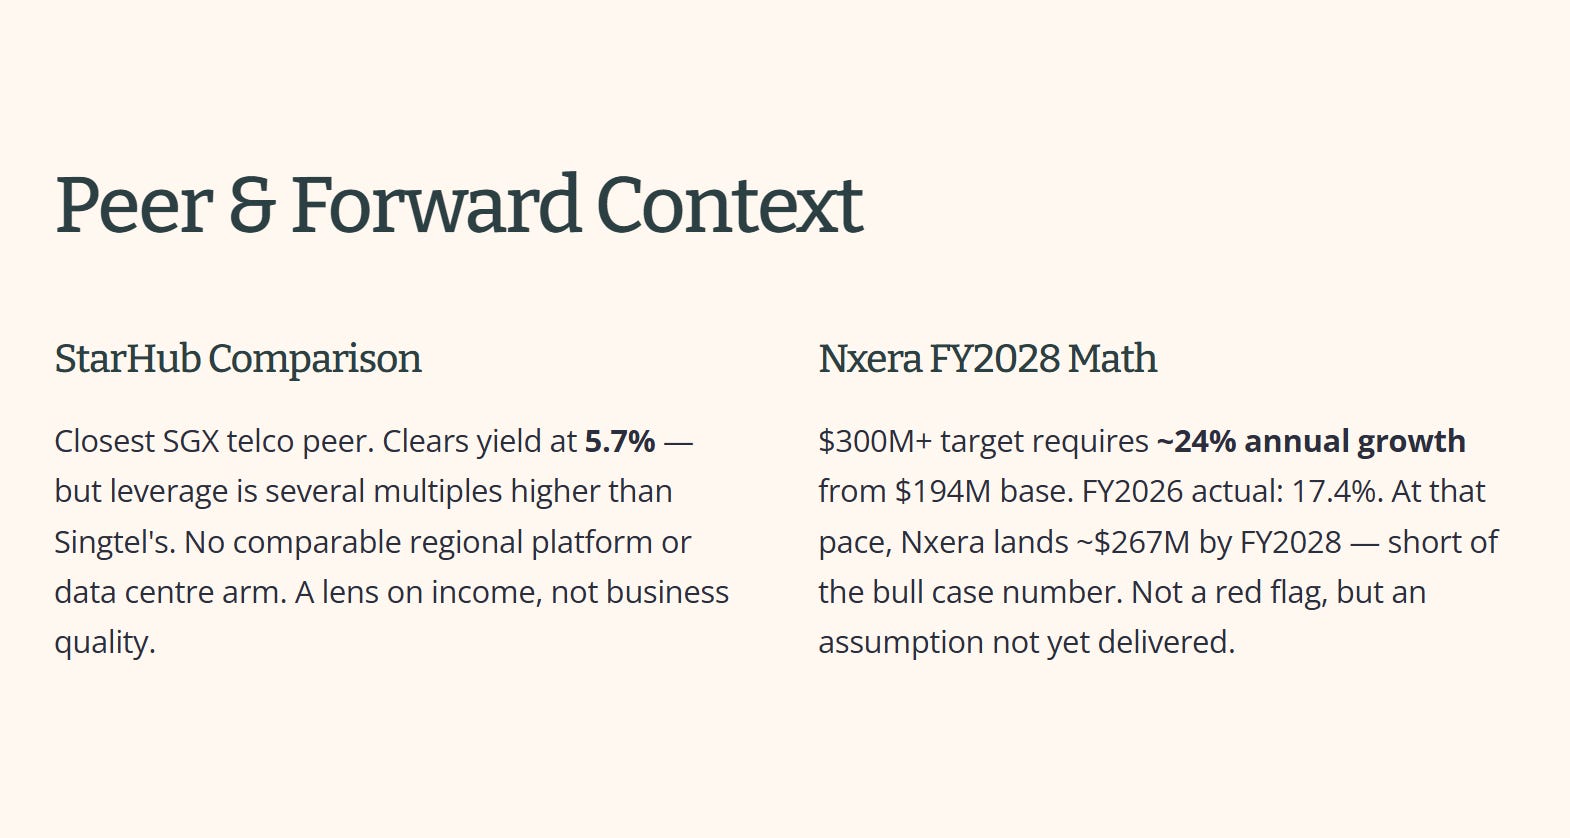
Layer four, forward scenario. FY2028 EBITDA above $300 million requires Nxera to grow at roughly 24% a year from its FY2026 base of $194 million. FY2026’s actual growth was 17.4%. Continue at that pace instead of accelerating, and Nxera lands closer to $267 million by FY2028, short of the number the bull case needs. That’s not a red flag on its own, growing businesses do accelerate, but it means the FY2028 target embeds an assumption Nxera hasn’t yet delivered.
Layer five, what this means for your wallet. If you’re holding Singtel for income today, the 4.3% headline yield already sits below what I’d want before recommending new capital into a CPF or SRS income sleeve, and stripped of the one-off dividend, the sustainable number is closer to 3%, below what CPF SA already pays without taking on any equity risk at all. That’s the same math whether you’re comparing it to your CPF SA rate over kopi at the void deck or running it through a spreadsheet. If you’re holding it to participate in the data centre growth story instead, this is closer to a growth allocation than an income one, and probably deserves to be sized and judged that way.
The Dividend Trajectory
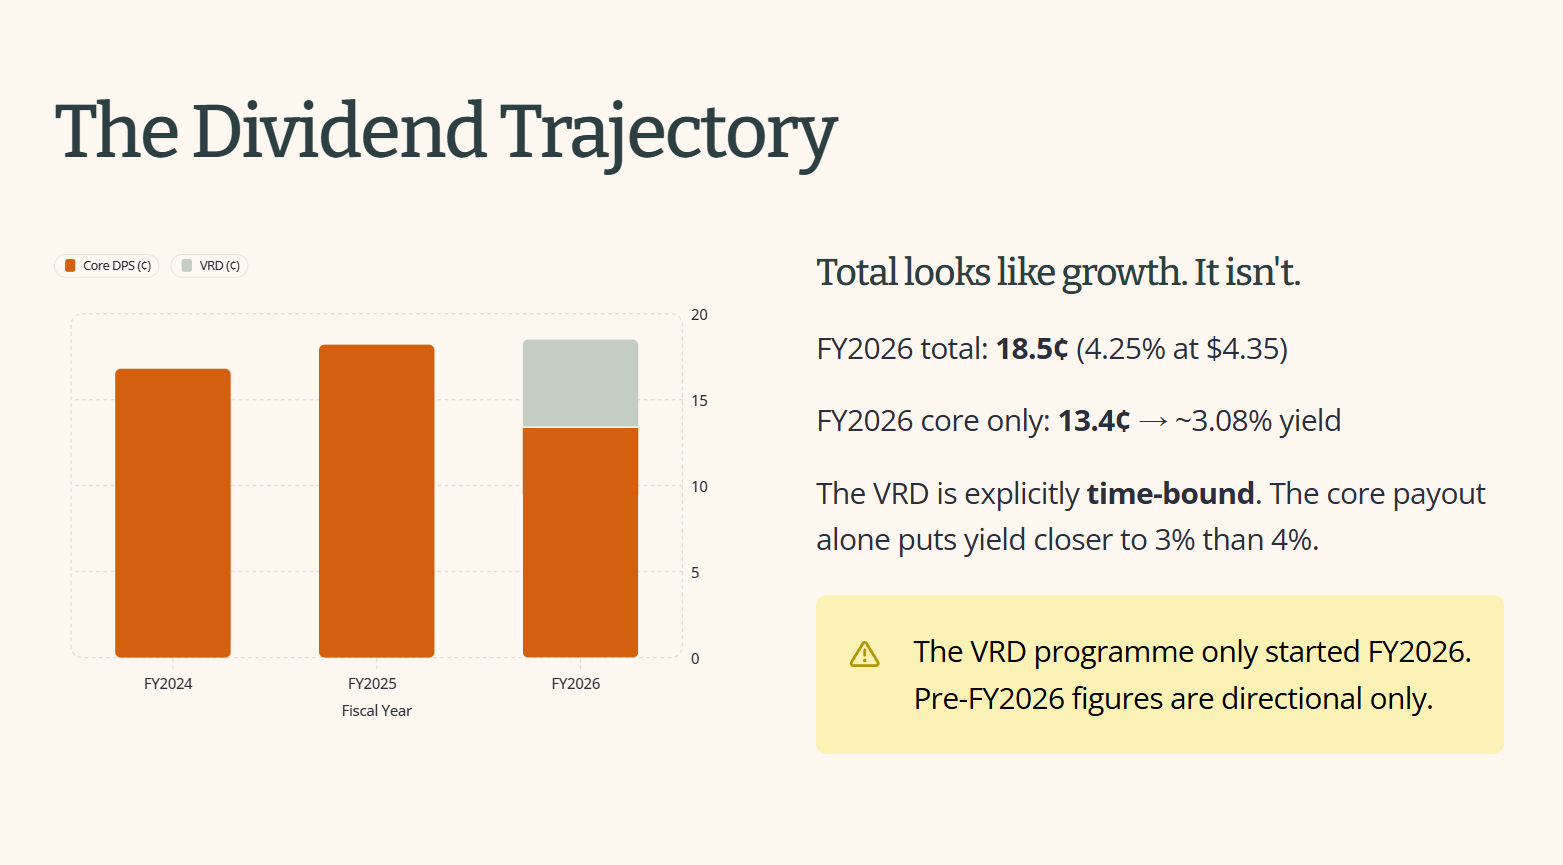
Note on the table above: pre-FY2026 figures come from calendar-year ex-dates rather than a clean fiscal-year cut, since Singtel’s own investor relations page and third-party dividend trackers don’t group these identically. Treat FY2024 and FY2025 as directional. The core versus VRD split only exists from FY2026 onward, since the Value Realisation Dividend programme itself only started that year.
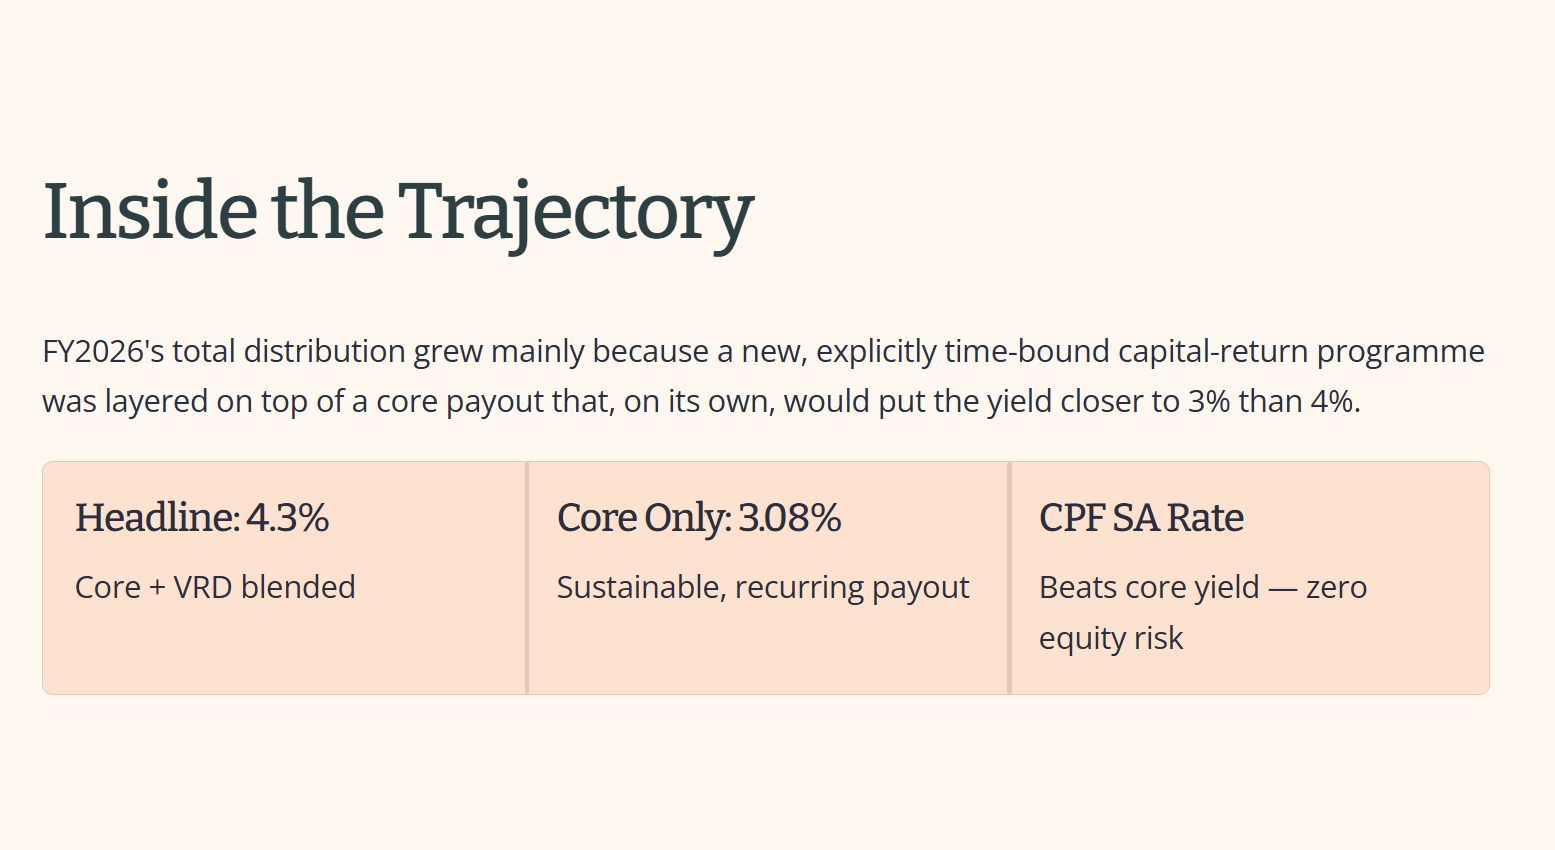
The trajectory looks like steady growth on the total line. It isn’t, once you see what’s inside it. FY2026’s total distribution grew mainly because a new, explicitly time-bound capital-return programme was layered on top of a core payout that, on its own, would put the yield closer to 3% than 4%.
The Forensic Gap
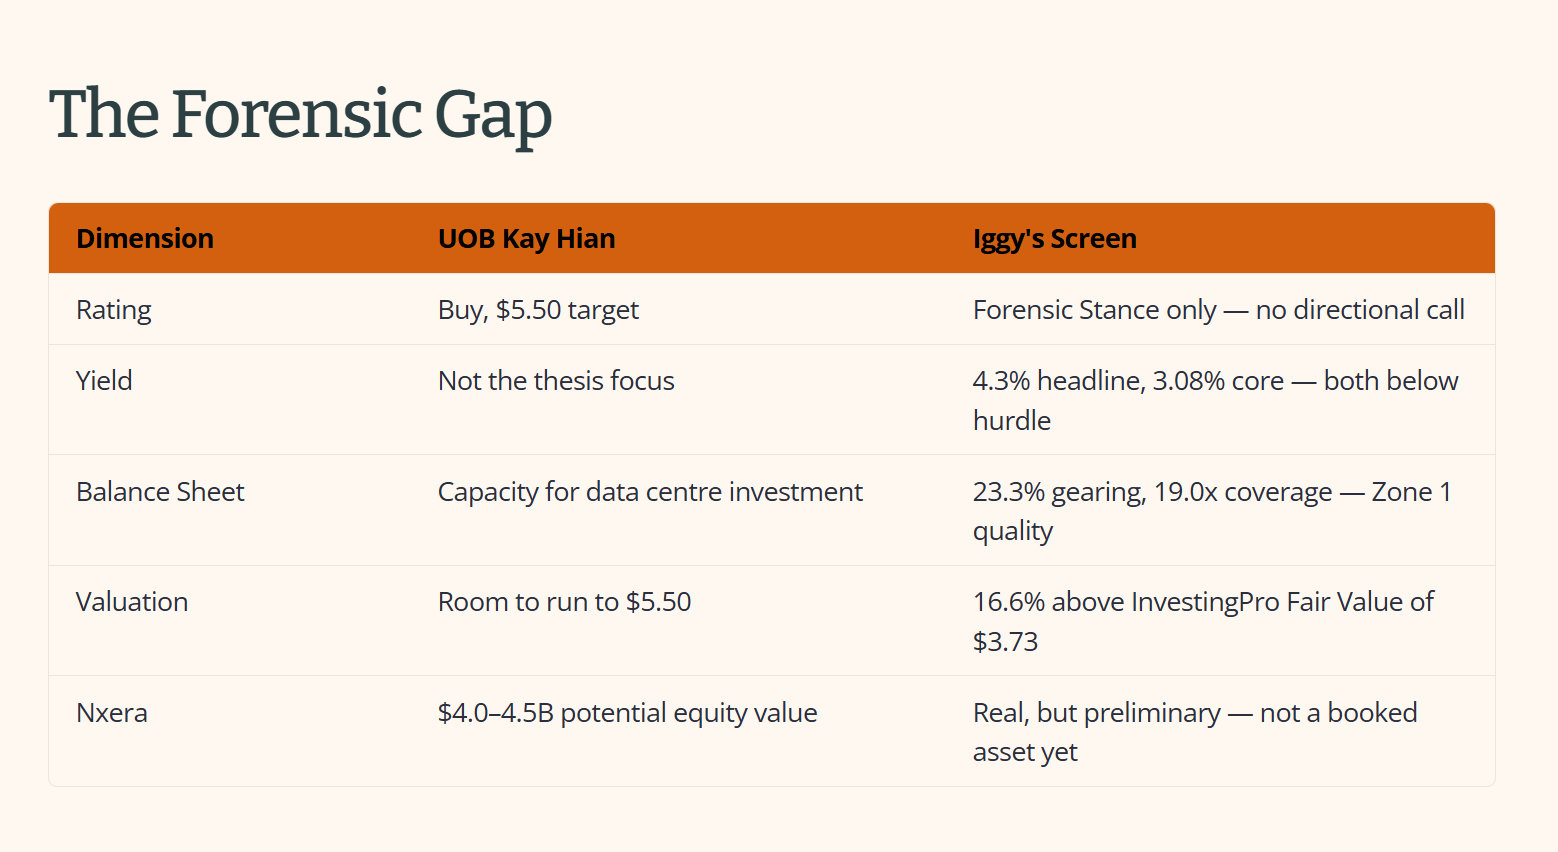
Brokers sell hope and price targets, but my screen only audits cold, hard cash. While UOB Kay Hian slaps on a "Buy" with an aggressive five dollars and fifty cents target by banking on future data centre hype, our forensic screen refuses to make speculative directional calls. Look past the story: the four point three percent headline yield and three point zero eight percent core yield both fail our four point seven percent editorial hurdle, meaning income investors simply aren't getting paid enough to take on equity risk here.
Yes, the balance sheet sits firmly in Zone 1 quality with a pristine twenty-three point three percent gearing and nineteen times coverage, but the stock is already trading sixteen point six percent above fair value, with unbooked pipeline dreams priced in as if the money were already sitting in the bank.
🔒 What's Next
Both headline and core yield fail my hurdle, while gearing and coverage sit comfortably in Zone 1. What would actually move this zone verdict isn't the target price, it's three specific triggers I'm tracking below.
