


The S$1.1 Billion Question Behind Venture’s Dividend Raise
A 20% interim dividend hike, a fortress balance sheet, and a cash flow number that doesn’t quite add up.
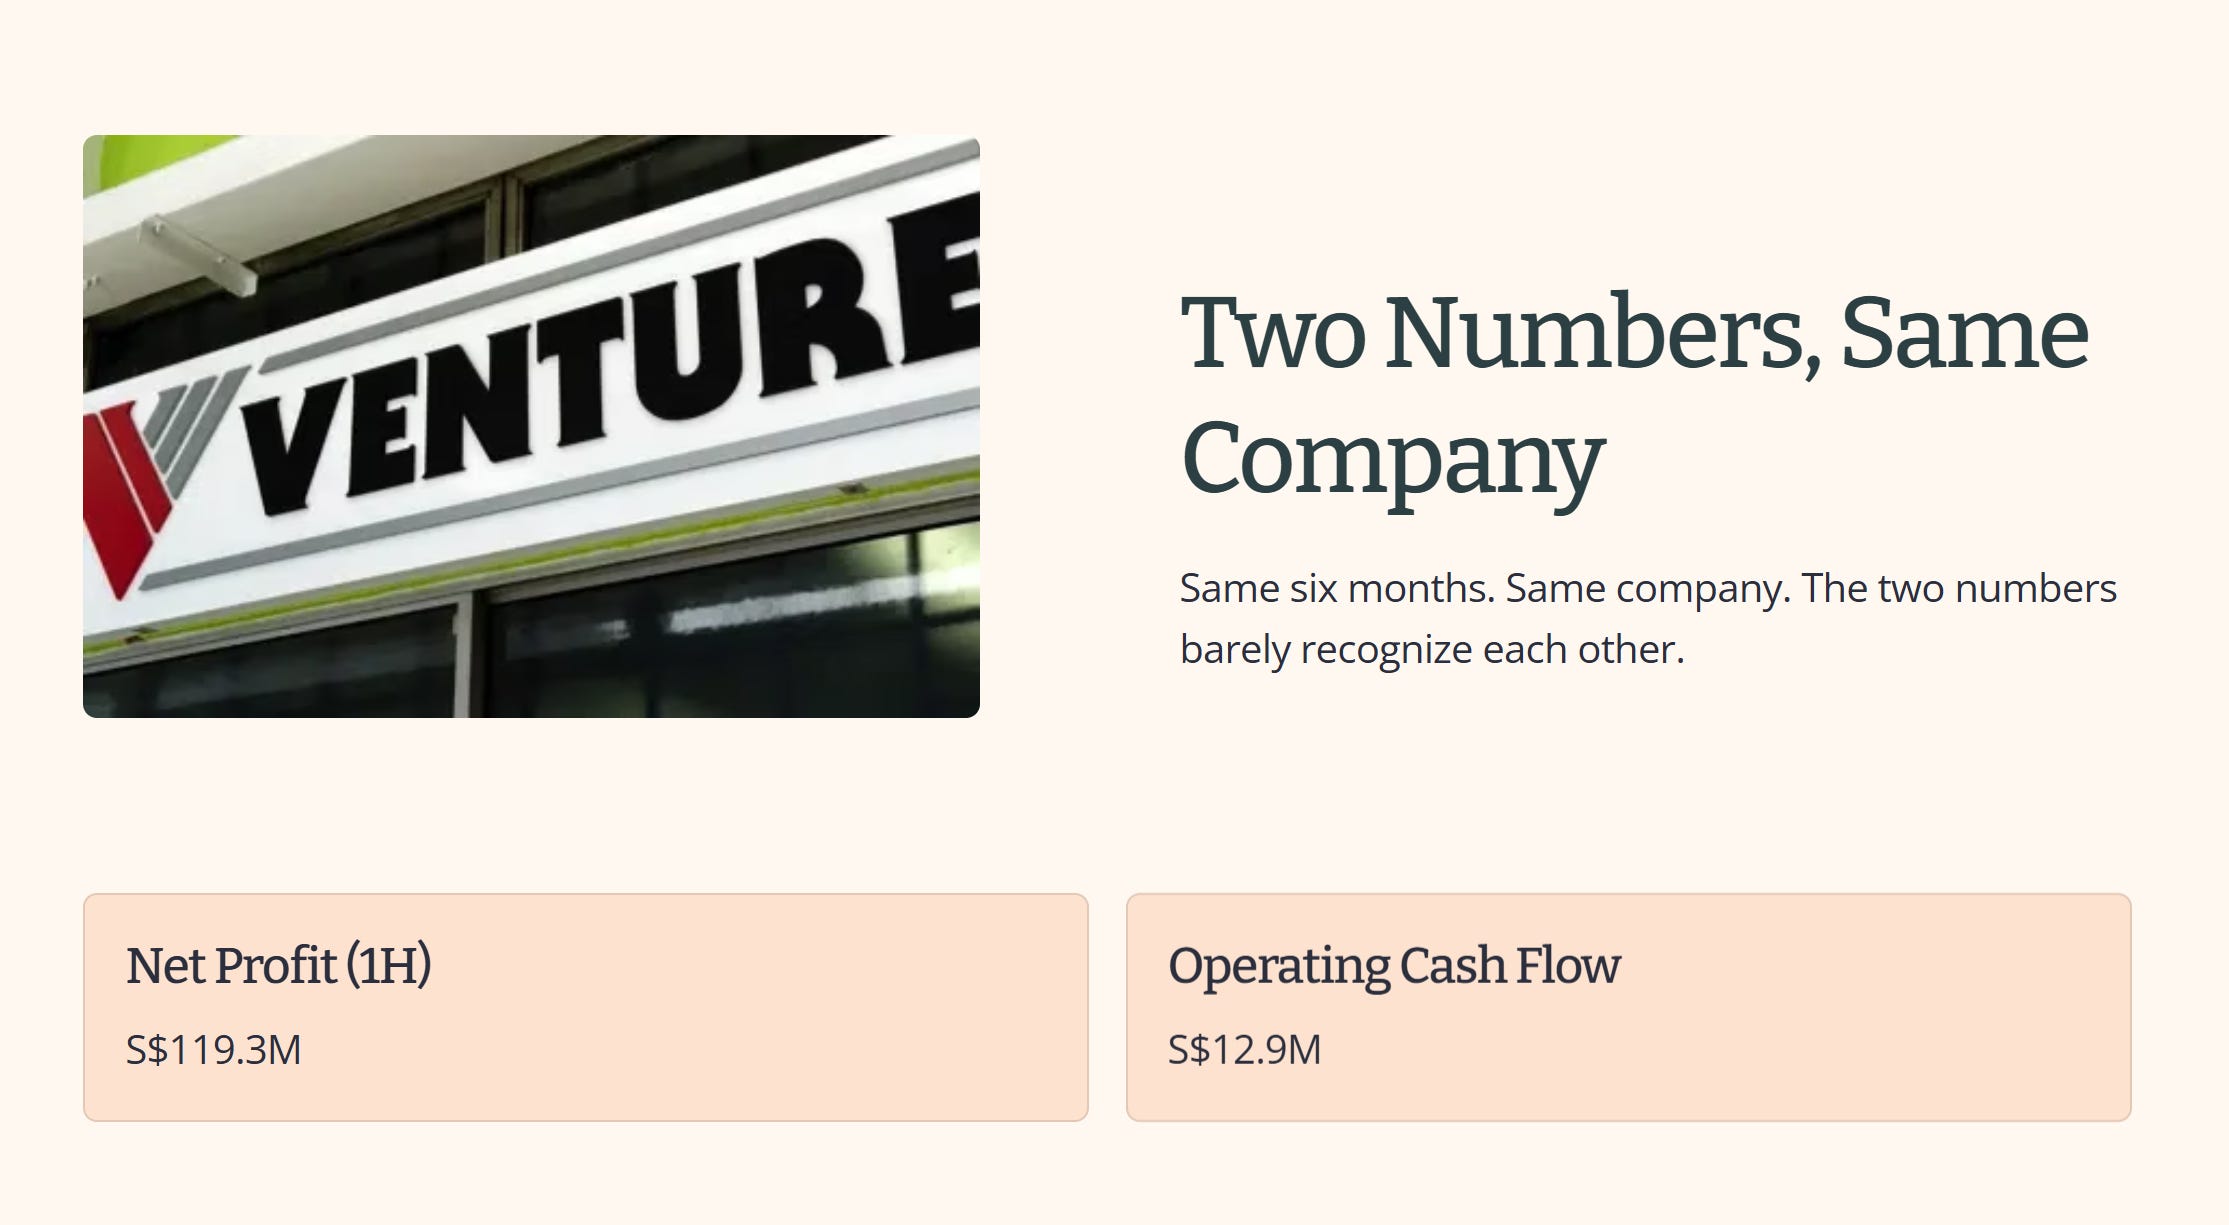
Venture just raised its dividend 20% on the strength of a S$119.3 million half-year profit. Its net cash generated from operating activities for that same half was S$12.9 million, about a tenth of the profit figure. Same six months, same company, and the two numbers barely recognize each other.
If you already hold Venture, this is good news you don’t need me to explain twice, the raise is real and your yield-on-cost just improved. If you’re deciding whether today’s S$16.67 is a fresh entry point, the balance sheet says yes and the cash flow statement says wait. I dug through both halves of that story so you don’t have to reconcile them yourself. Let’s get into it.
Iggy’s Forensic Zone: Zone 2, Watchlist
Three Gems: What Venture Got Genuinely Right
Gem 1: The fortress didn’t just hold, it’s still standing at scale
Gem 2: The growth is real, not a one-quarter pop
Gem 3: The yield clears my hurdle, barely, but for real
Legacy Holders vs. Fresh Capital
The Financial Health Checklist
The Window Is Already Open
The Dividend Trajectory
Iggy’s Insight
Three Red Flags: What The Cash Flow Actually Says
Red Flag 1: Operating cash flow badly lagged the profit line this half
Red Flag 2: Returns on that giant cash pile have been sliding for years
Red Flag 3: The market has already priced in a fair amount of the good news
Valuation Snapshot
What To Watch Next
Iggy’s Insight
Closing: The Verdict
Three Gems: What Venture Got Genuinely Right
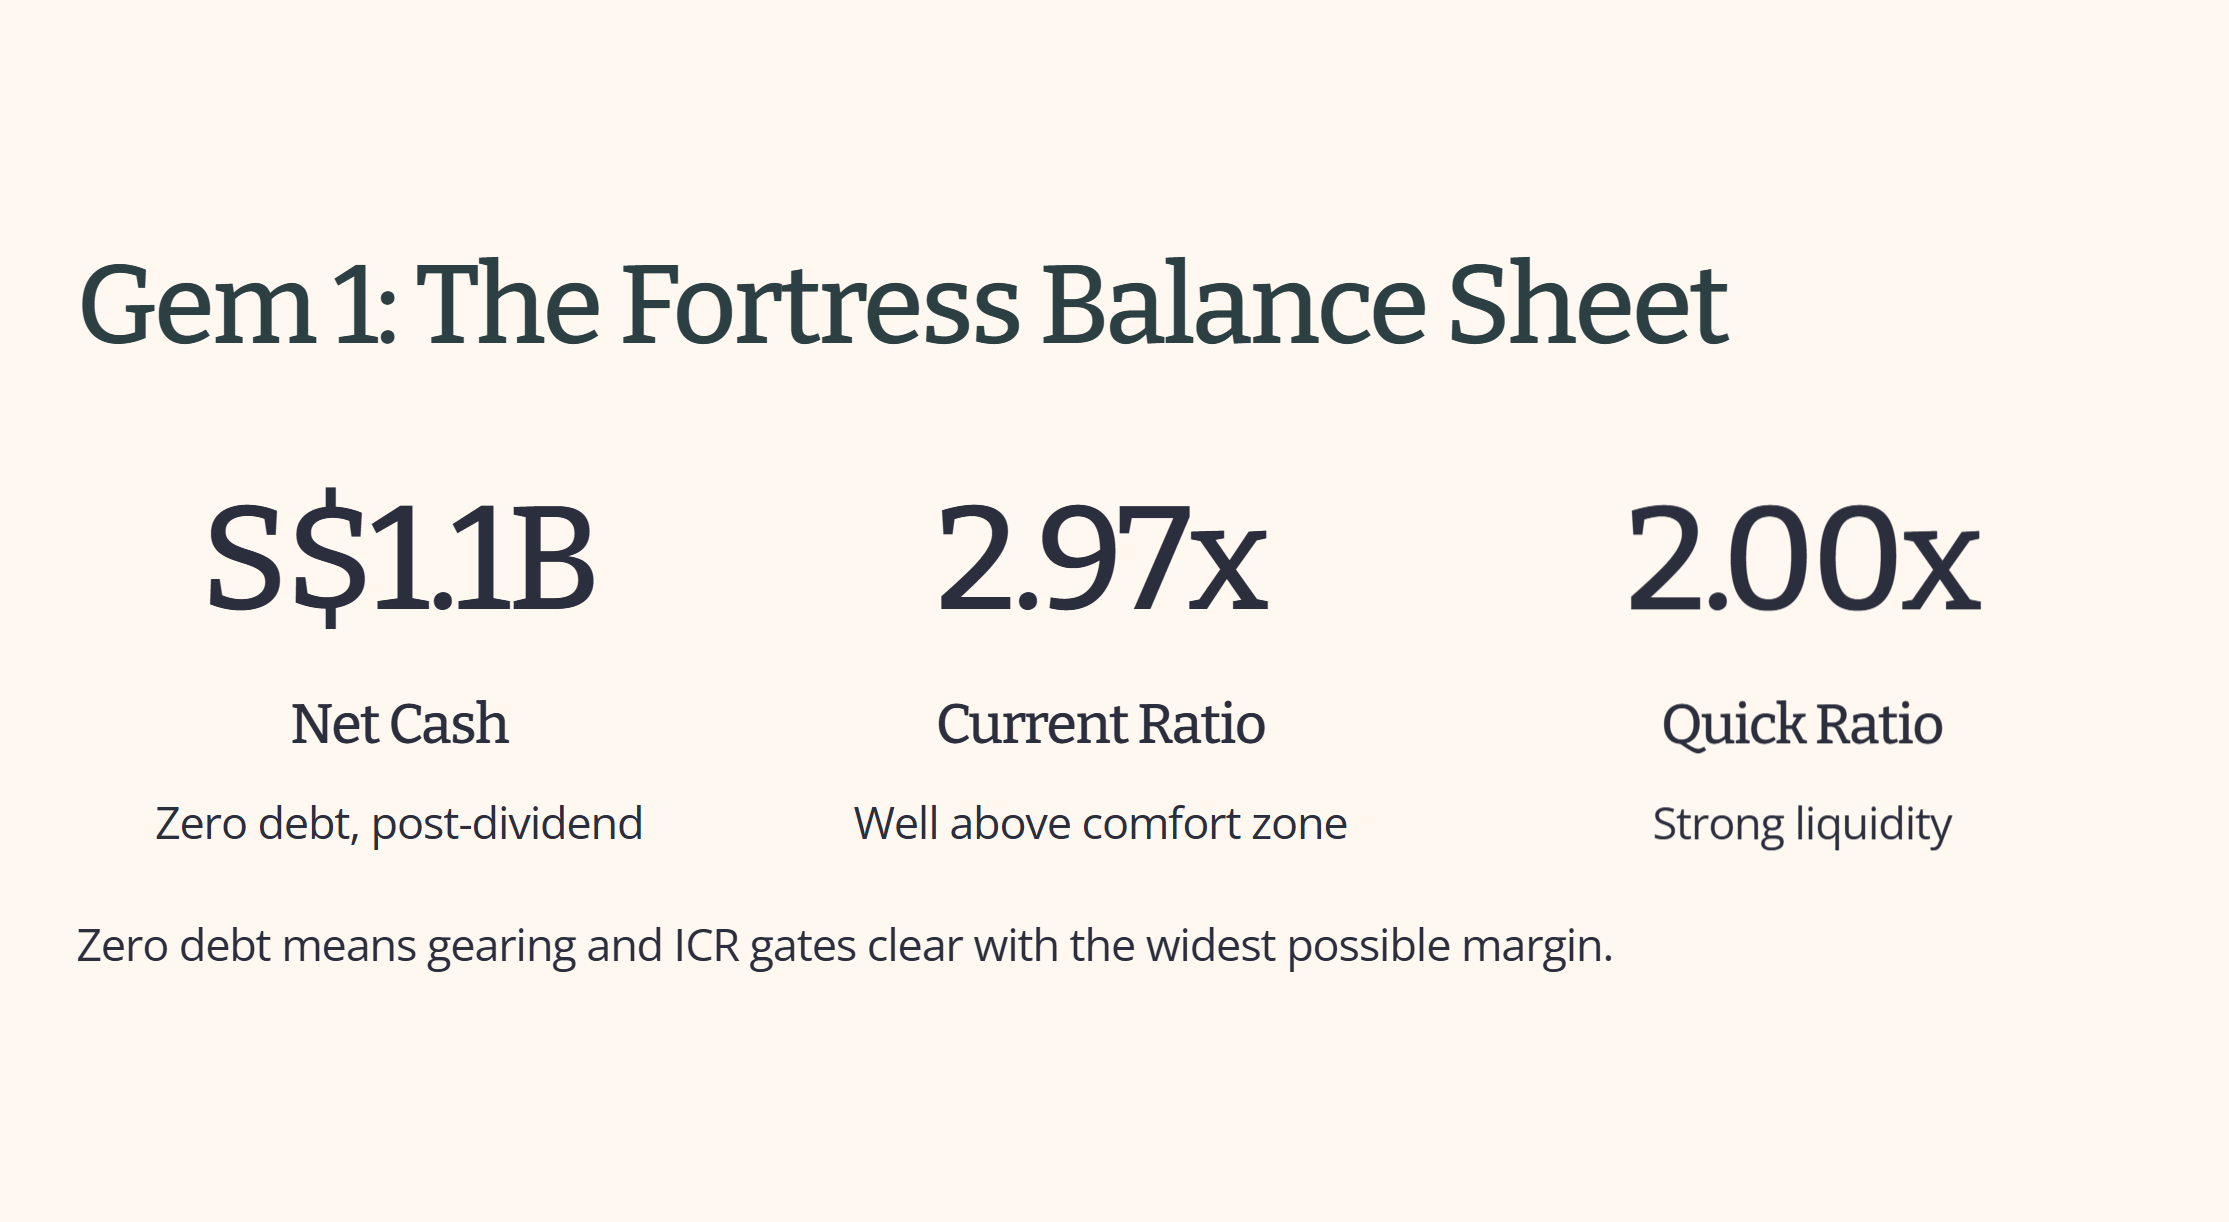
Gem 1: The fortress didn’t just hold, it’s still standing at scale. Venture closed 1H FY2026 with a net cash position of S$1,108.5 million and zero debt, even after paying out its S$143.8 million FY2025 final dividend on 19 May 2026. Current ratio sits at 2.97x, quick ratio at 2.00x. My gearing ceiling is 35% and my ICR floor is 4x, the interest coverage ratio, basically how many times over a company can pay the interest on its debt from operating earnings. Venture doesn’t have debt to test either gate against. Both clear with the widest possible margin.
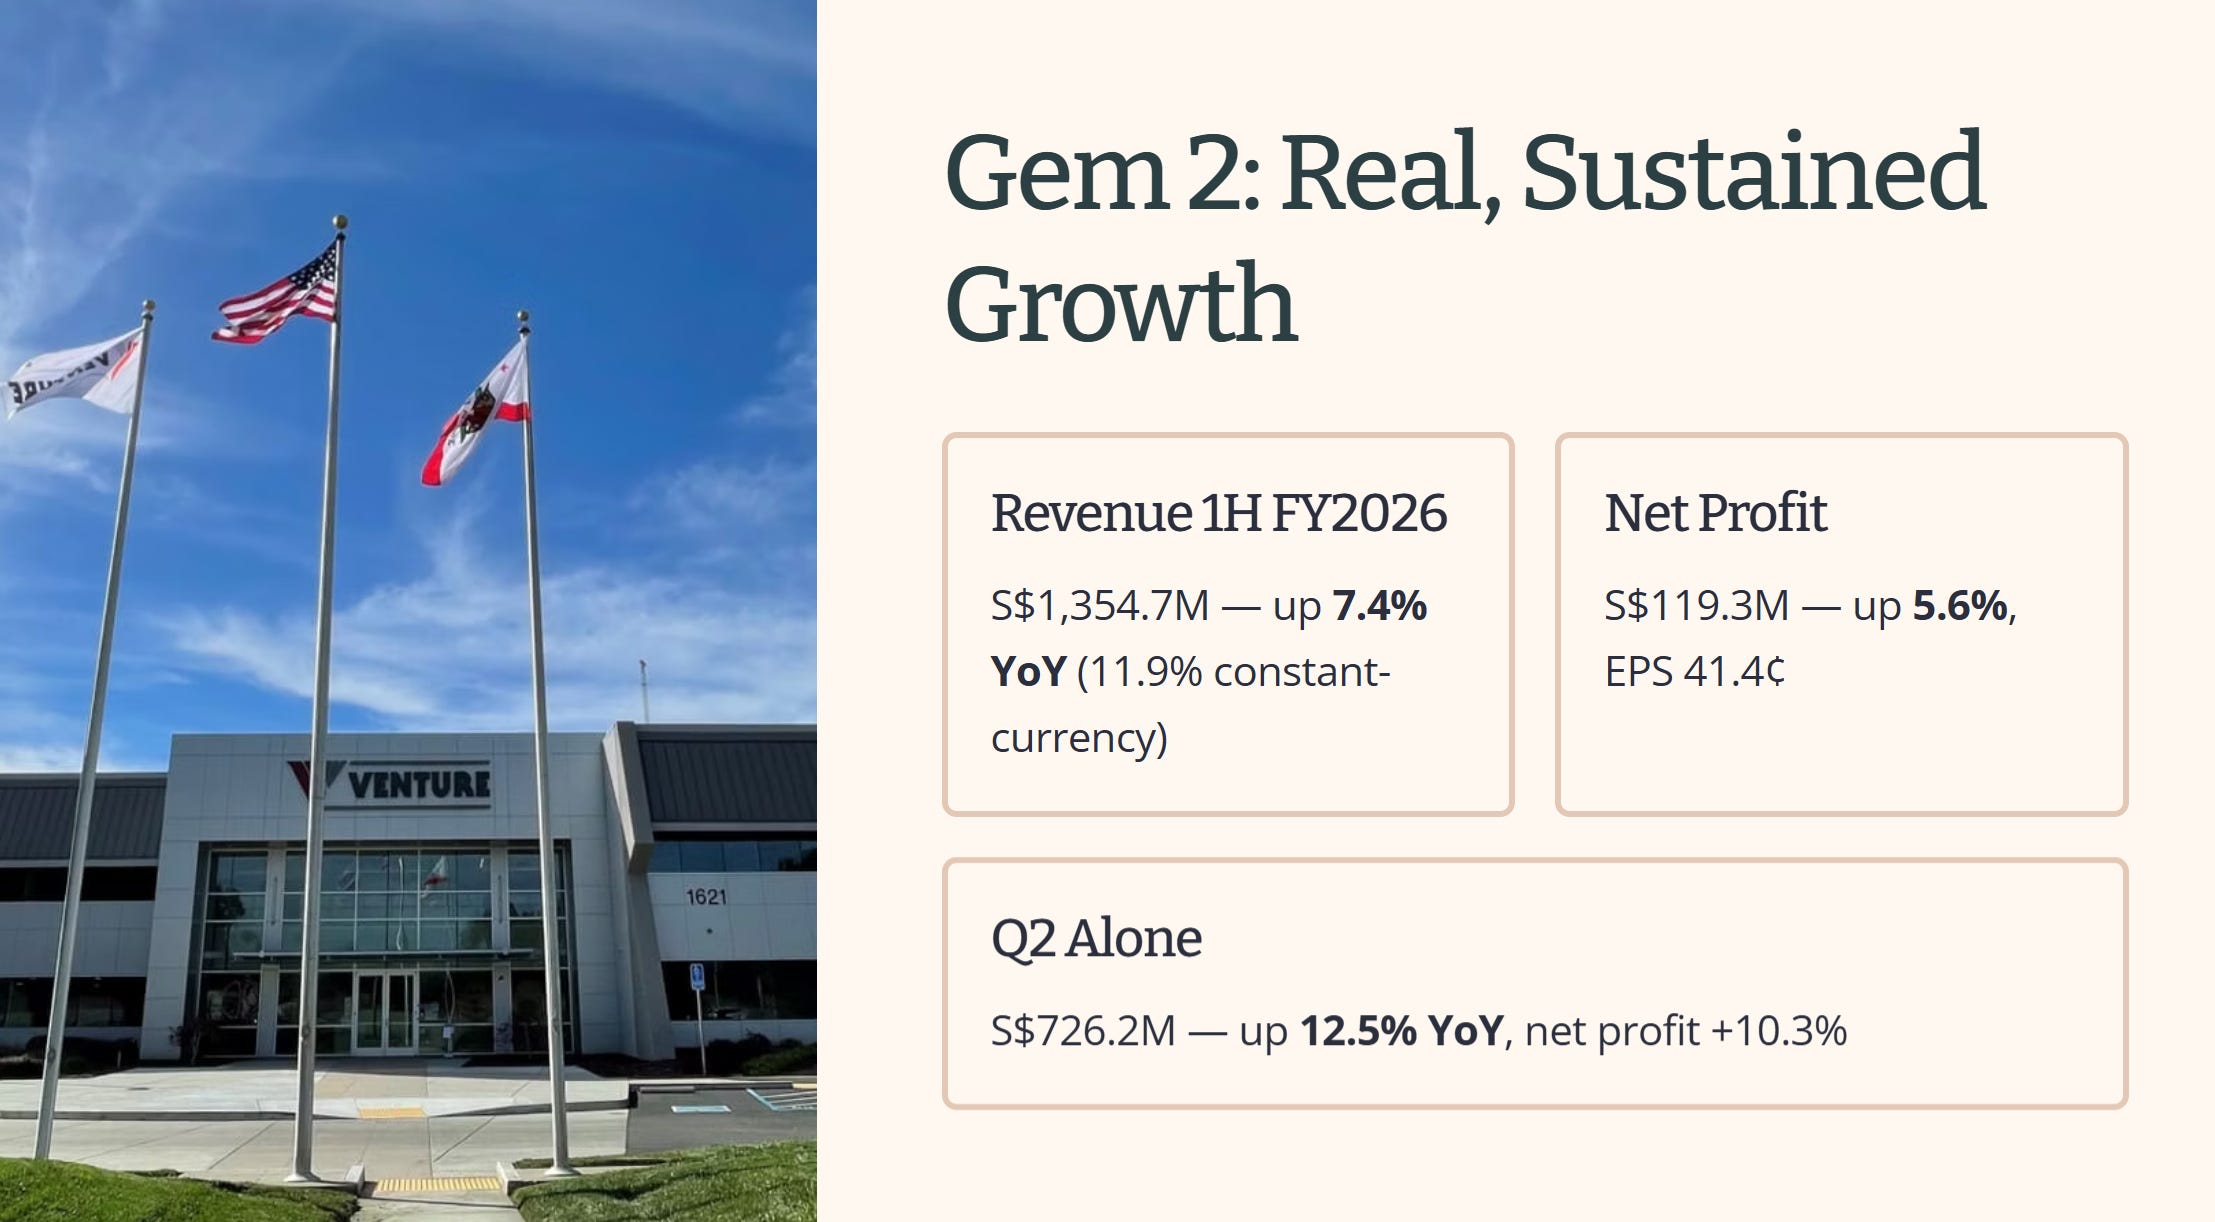
Gem 2: The growth is real, not a one-quarter pop. Revenue for 1H FY2026 came in at S$1,354.7 million, up 7.4% year on year (11.9% on a constant-currency basis), with net profit up 5.6% to S$119.3 million and EPS up the same 5.6% to 41.4 cents, a clean, consistent read across every profitability line. Q2 alone grew 12.5% year on year to S$726.2 million, with net profit up 10.3% for the quarter, so this wasn’t a single strong quarter skewing the half, Q1 FY2026 revenue was already up 1.9% year on year in reported terms (8.2% on a constant-currency basis) before Q2 built on it. Management’s own stated reason for the dividend raise was the improved result.
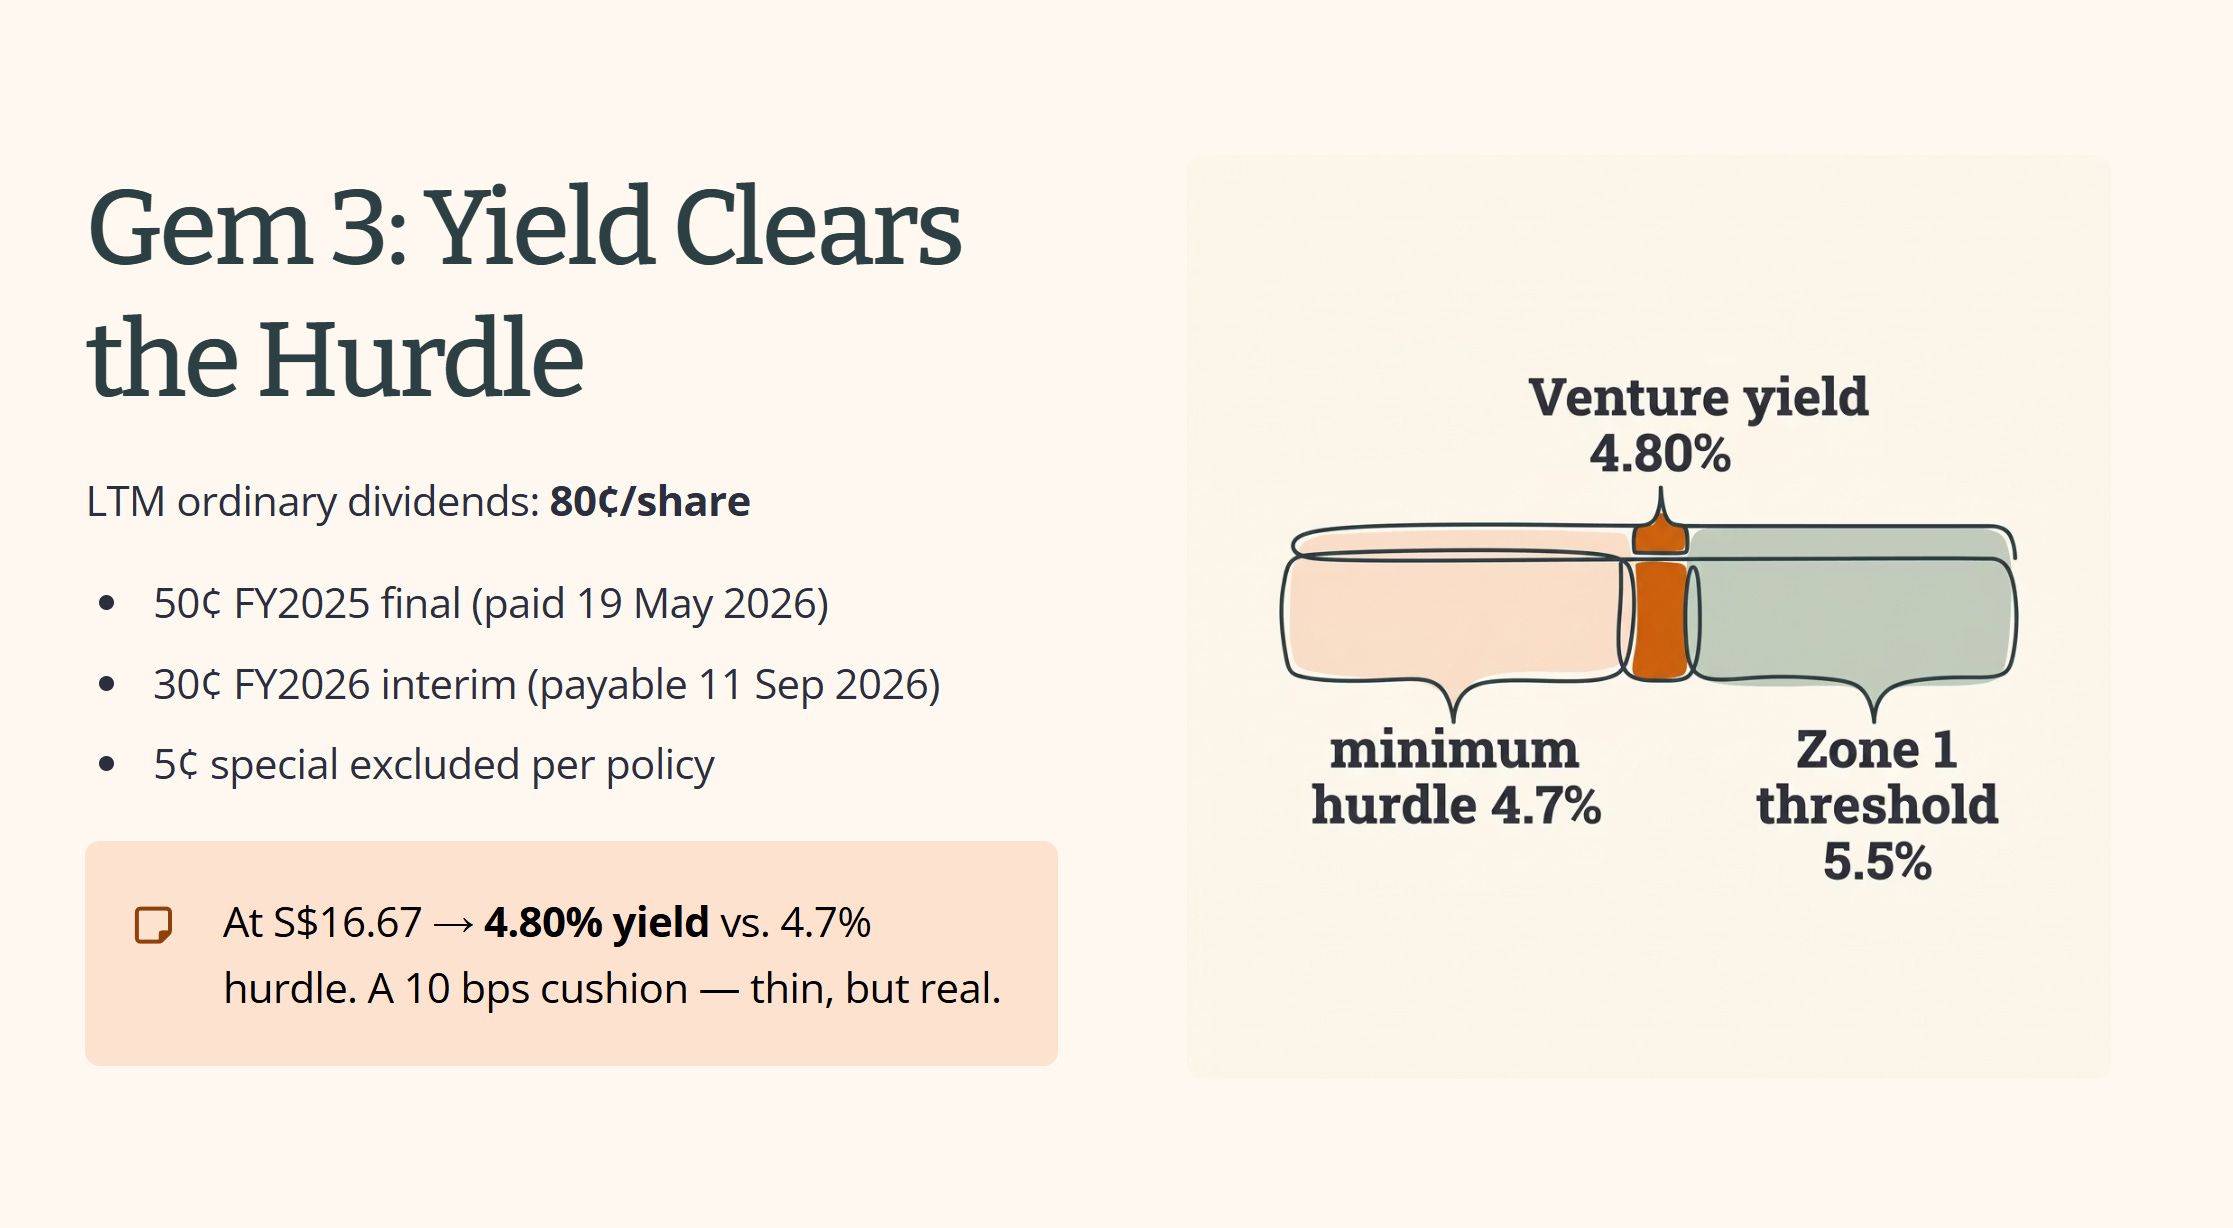
Gem 3: The yield clears my hurdle, barely, but for real. Last-twelve-month ordinary cash dividends now total 80 cents a share: the 50-cent FY2025 final (paid 19 May 2026) plus the newly confirmed 30-cent FY2026 interim (payable 11 September 2026). A separate 5-cent special dividend paid alongside 1H2025’s interim is excluded from this figure, per my standing policy of never letting a one-off special inflate the yield I actually screen against. At S$16.67, that’s a yield of 4.80%, clearing my 4.7% minimum hurdle. I won’t dress that up as comfortable. It’s a 10 basis point cushion, thinner than I’d like on a name I’m calling a genuine gem.
Legacy Holders vs. Fresh Capital
This is a real, disclosed distribution change on a widely-held name, so this section isn’t optional.
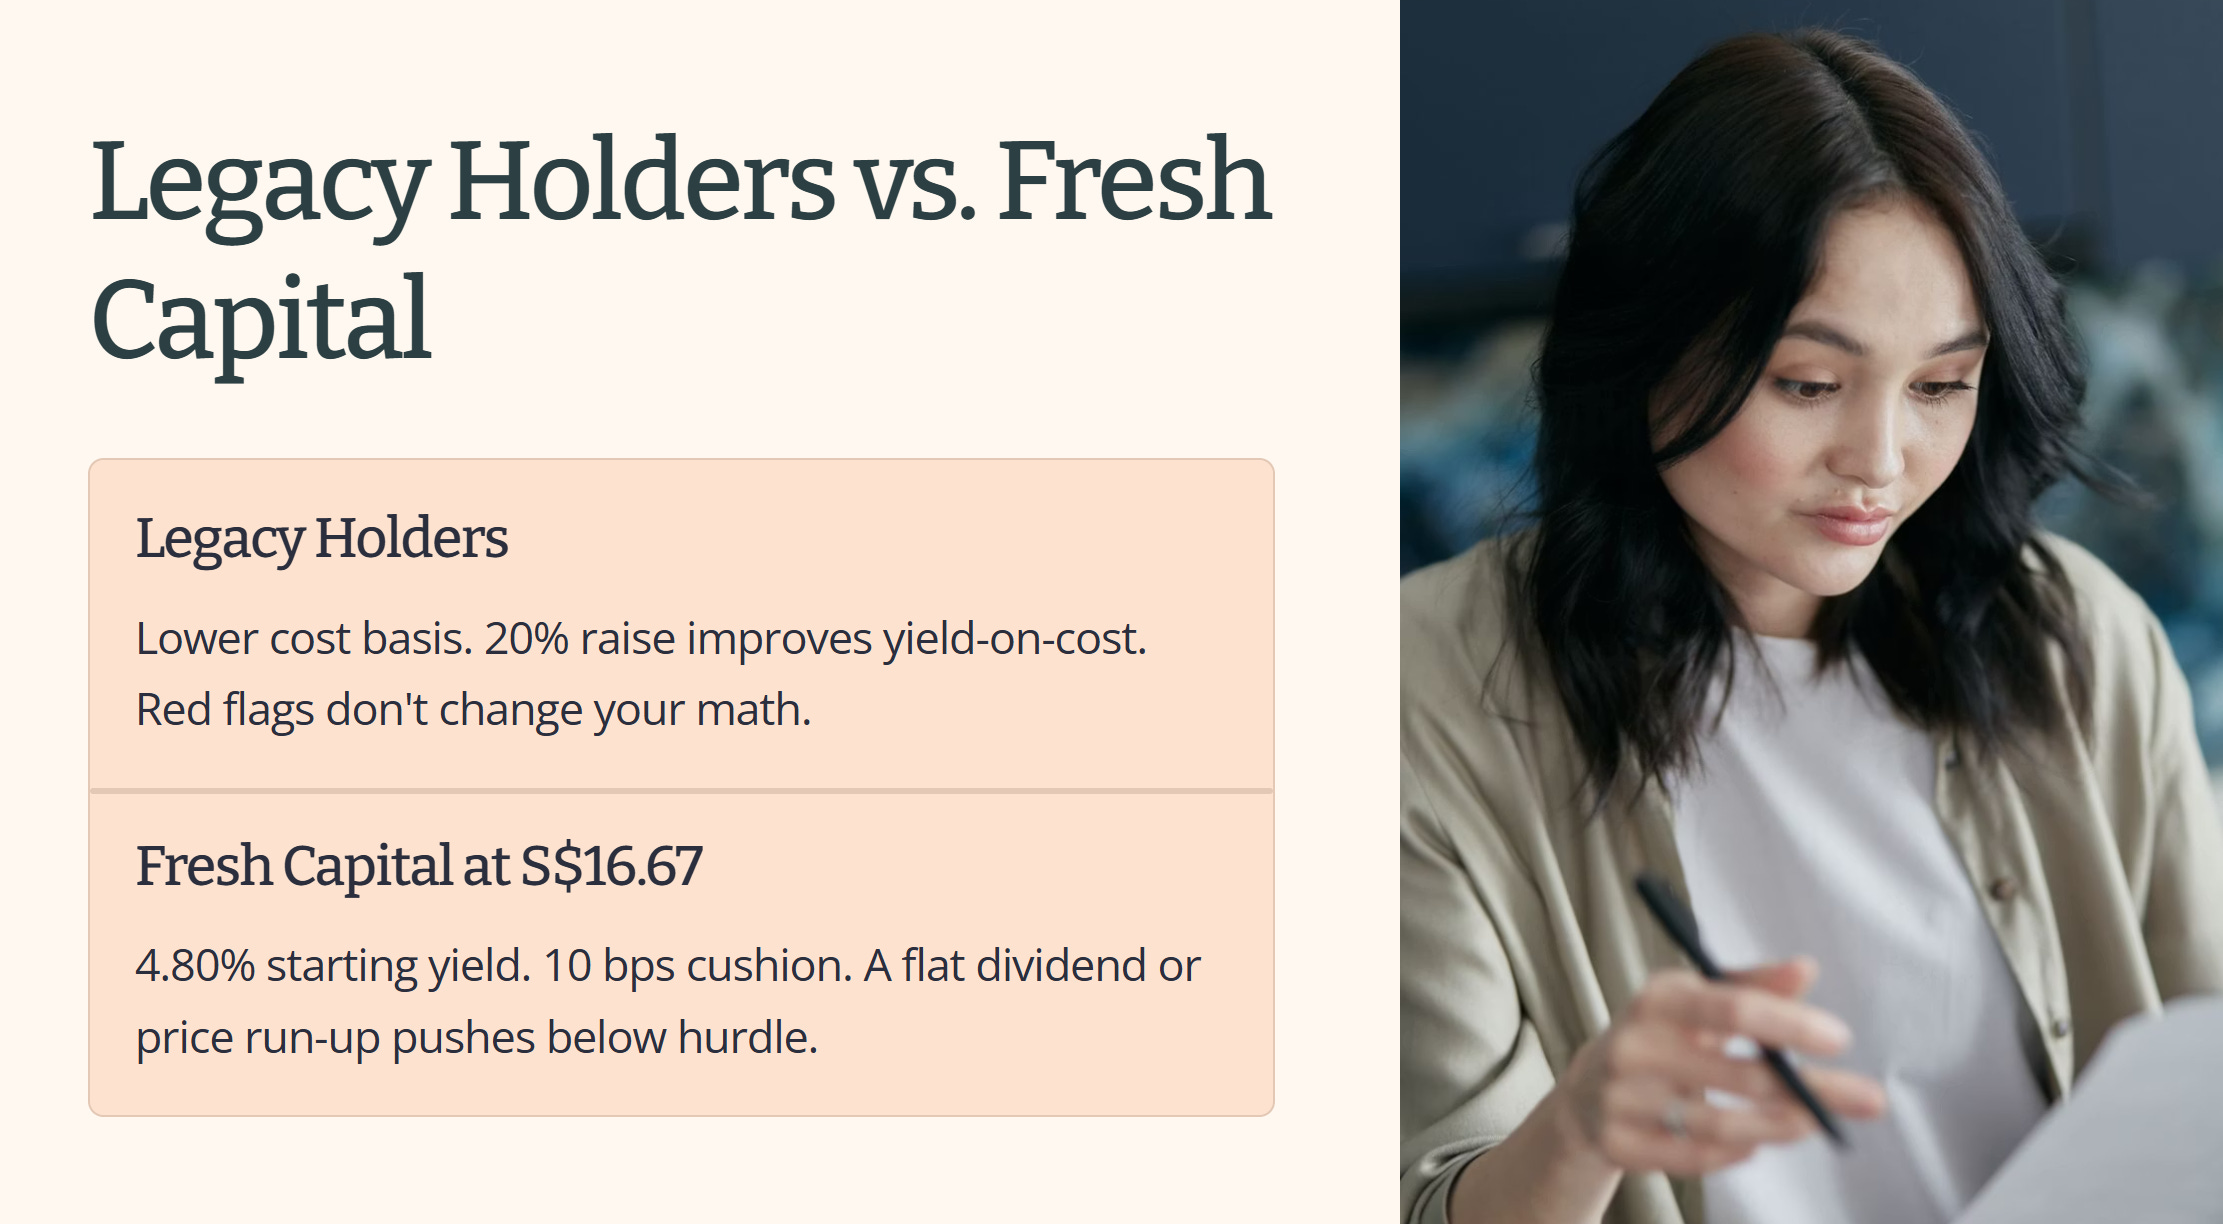
If you bought Venture years ago at a meaningfully lower cost basis, this 20% raise just improved your yield-on-cost in a way that matters, and nothing in the red flags below changes that math for you. If you’re weighing fresh capital at today’s S$16.67, you’re buying into a 4.80% starting yield with a 10 basis point cushion above my hurdle, a much thinner margin of safety than a legacy holder’s effective return. A flat dividend next cycle, or a further run-up in the share price with no matching dividend growth, would be enough to push a fresh purchase below my hurdle.
The Financial Health Checklist
Strip away the balance sheet and the growth story and this is what’s left when you run Venture through every hard gate at once.
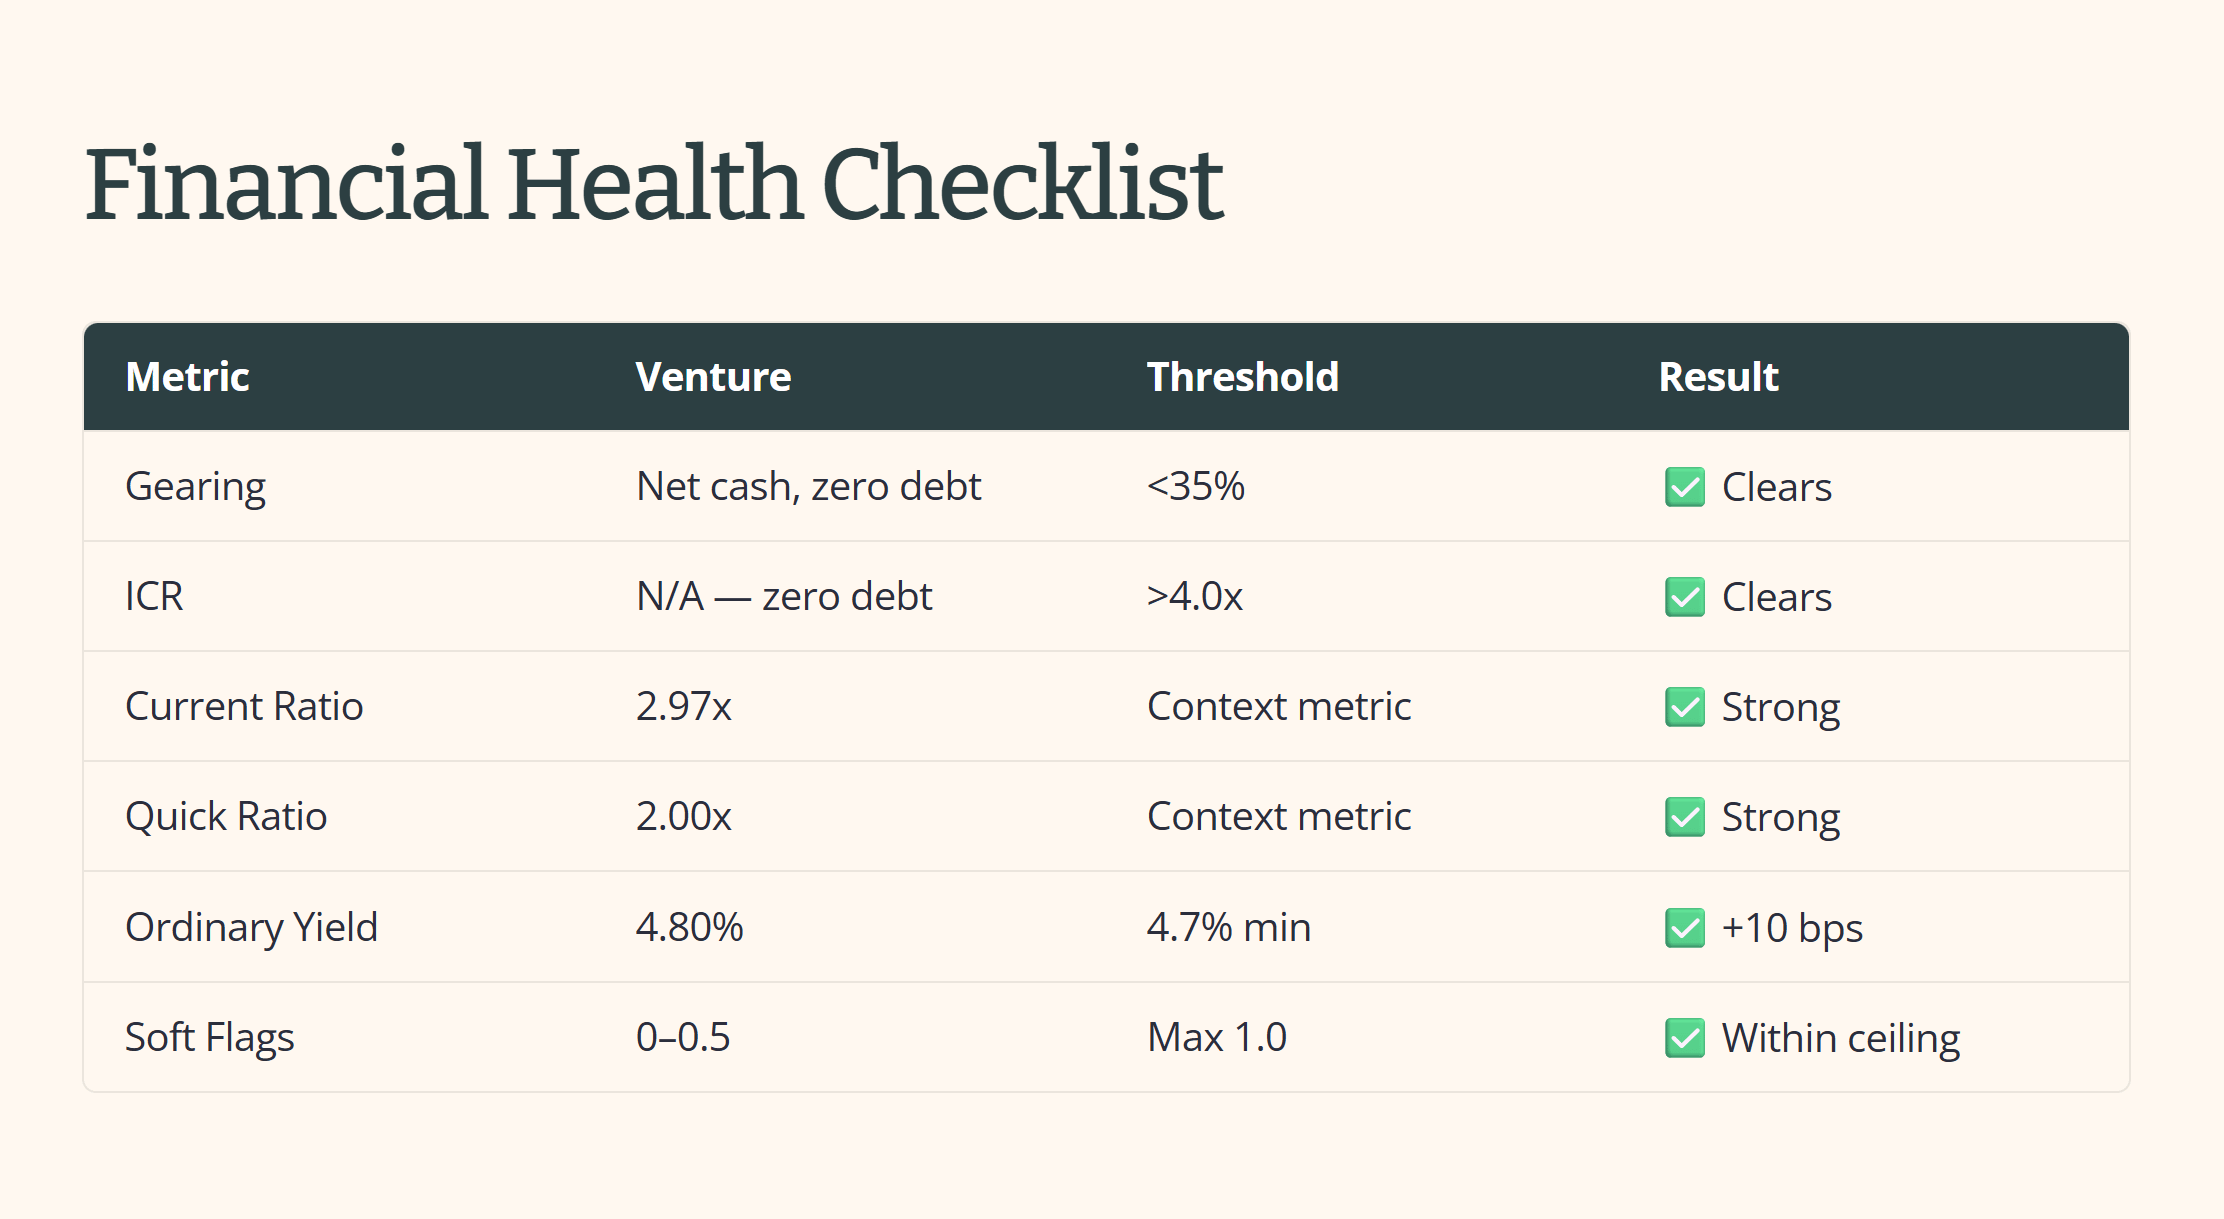
Six gates, six passes. Gearing and interest coverage clear automatically with zero debt on the books, there’s nothing left to service. Liquidity is well past comfortable on both the current and quick ratios. The one line that isn’t a clean pass by a wide margin is ordinary yield, ten basis points above the 4.7% floor, thin but real.
The soft flags row is where the cash flow story from earlier in this piece actually shows up on paper: the cash conversion gap is logged there as a discretionary 0.5 flag, still comfortably inside the 1.0 ceiling, but it’s the one number on this table worth watching move.
The Window Is Already Open
The Window Closes Fast. In this market, the difference between a “Sanctuary” and a “Yield Trap” is decided in a single trading session. By the time this analysis reaches you as a free subscriber, the entry window Iggy identified has already opened, and often closed.
Iggy’s Elite Investors don’t just get the report earlier. They get it when the numbers still matter, zero-day forensic breakdowns, the full “Red Zone” watchlist, and institutional-grade cheatsheets at the moment the setup is live, not after the market has already priced it in.
For S$12/month, less than two kopi and kaya toast sets at Raffles Place, you stop being the Exit Liquidity and start being the Analyst.
The Dividend Trajectory
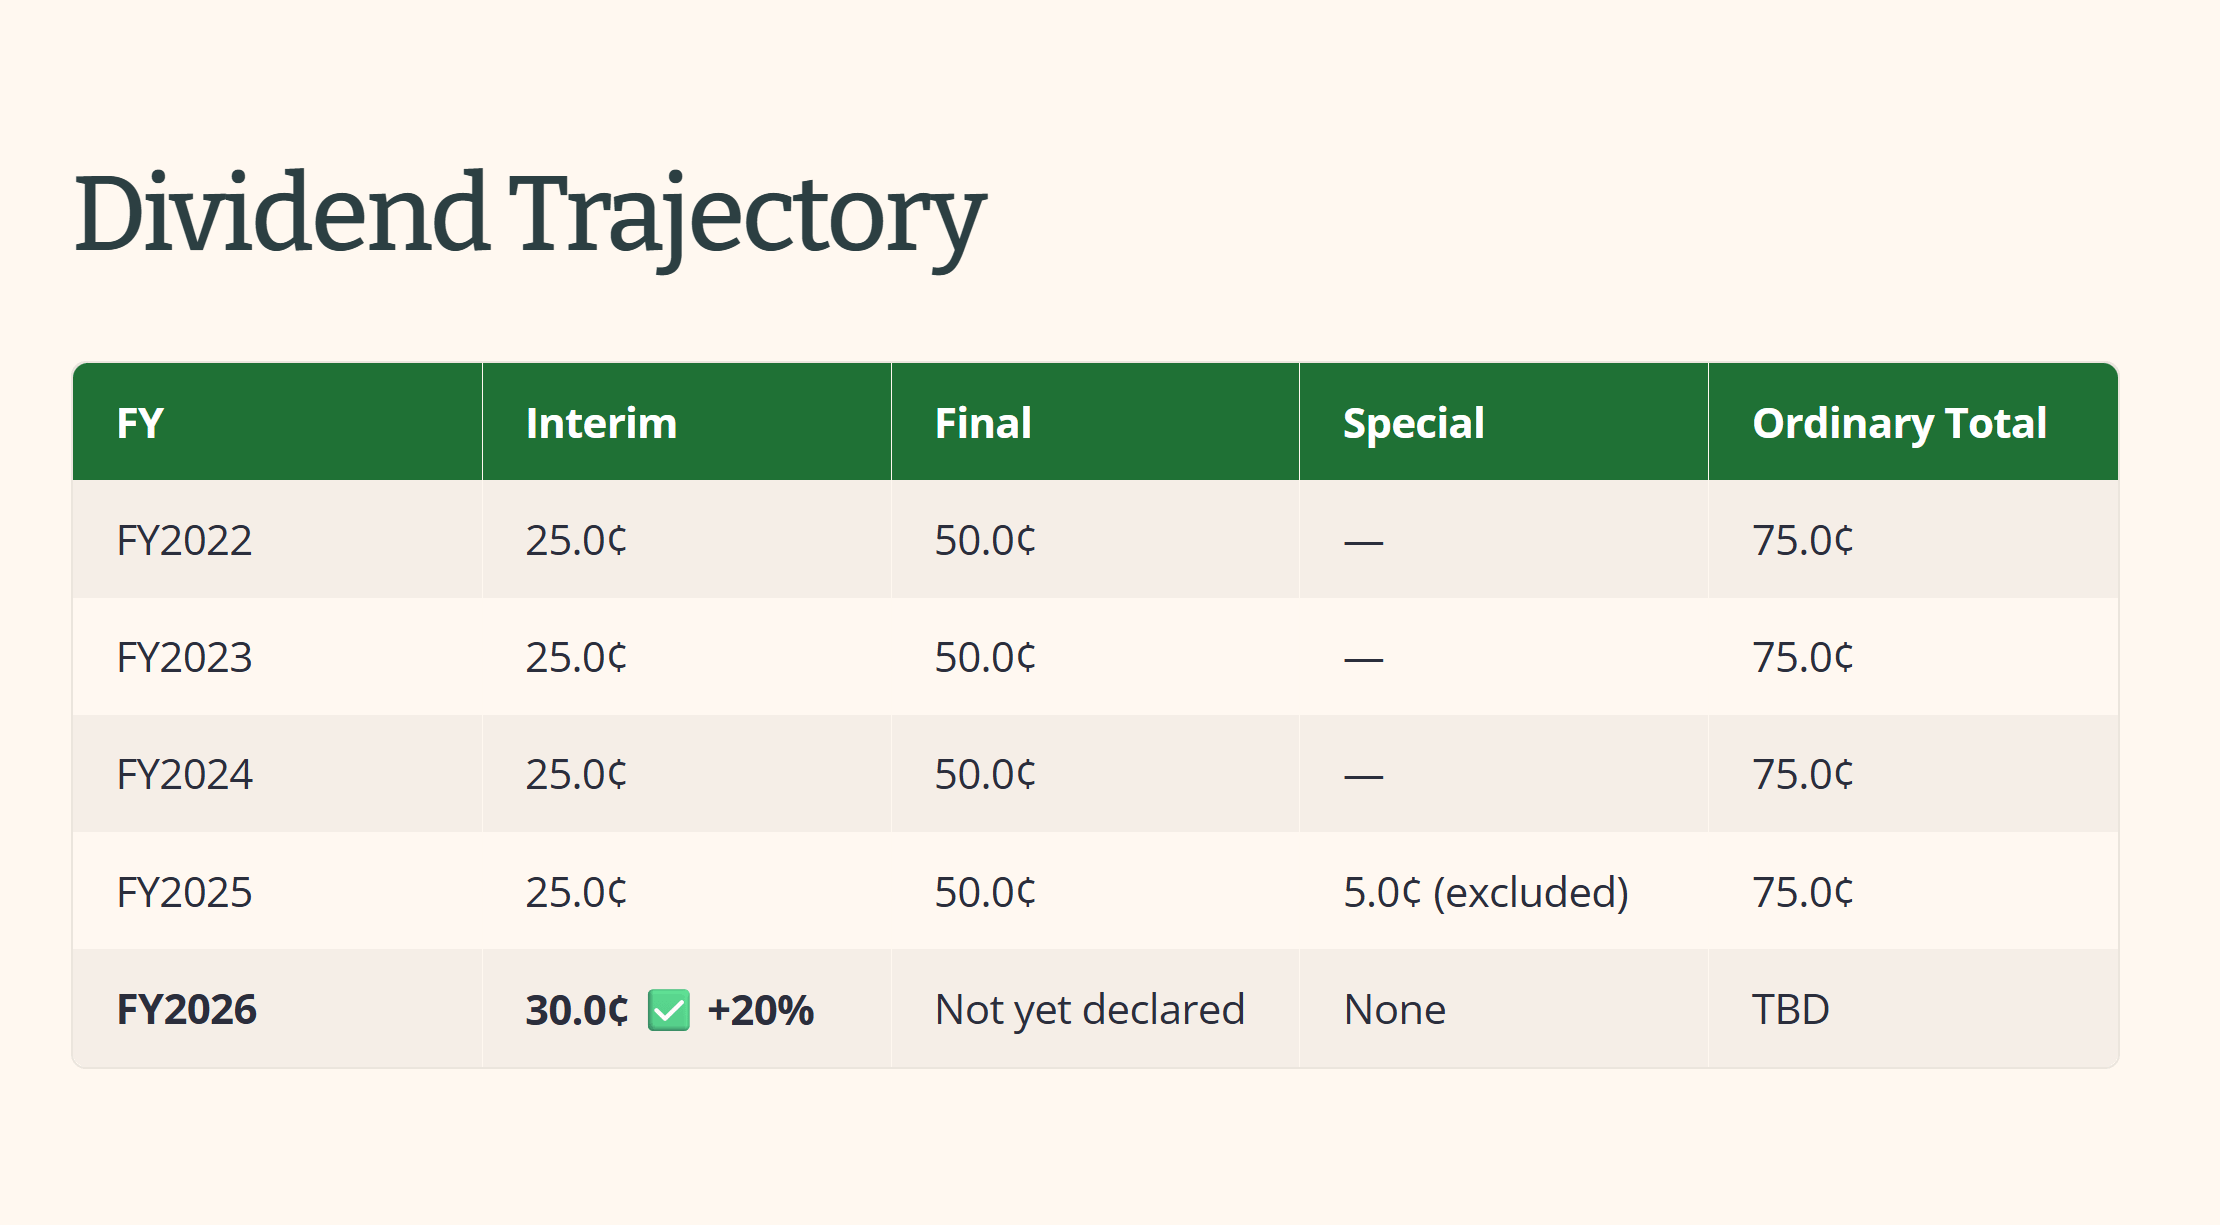
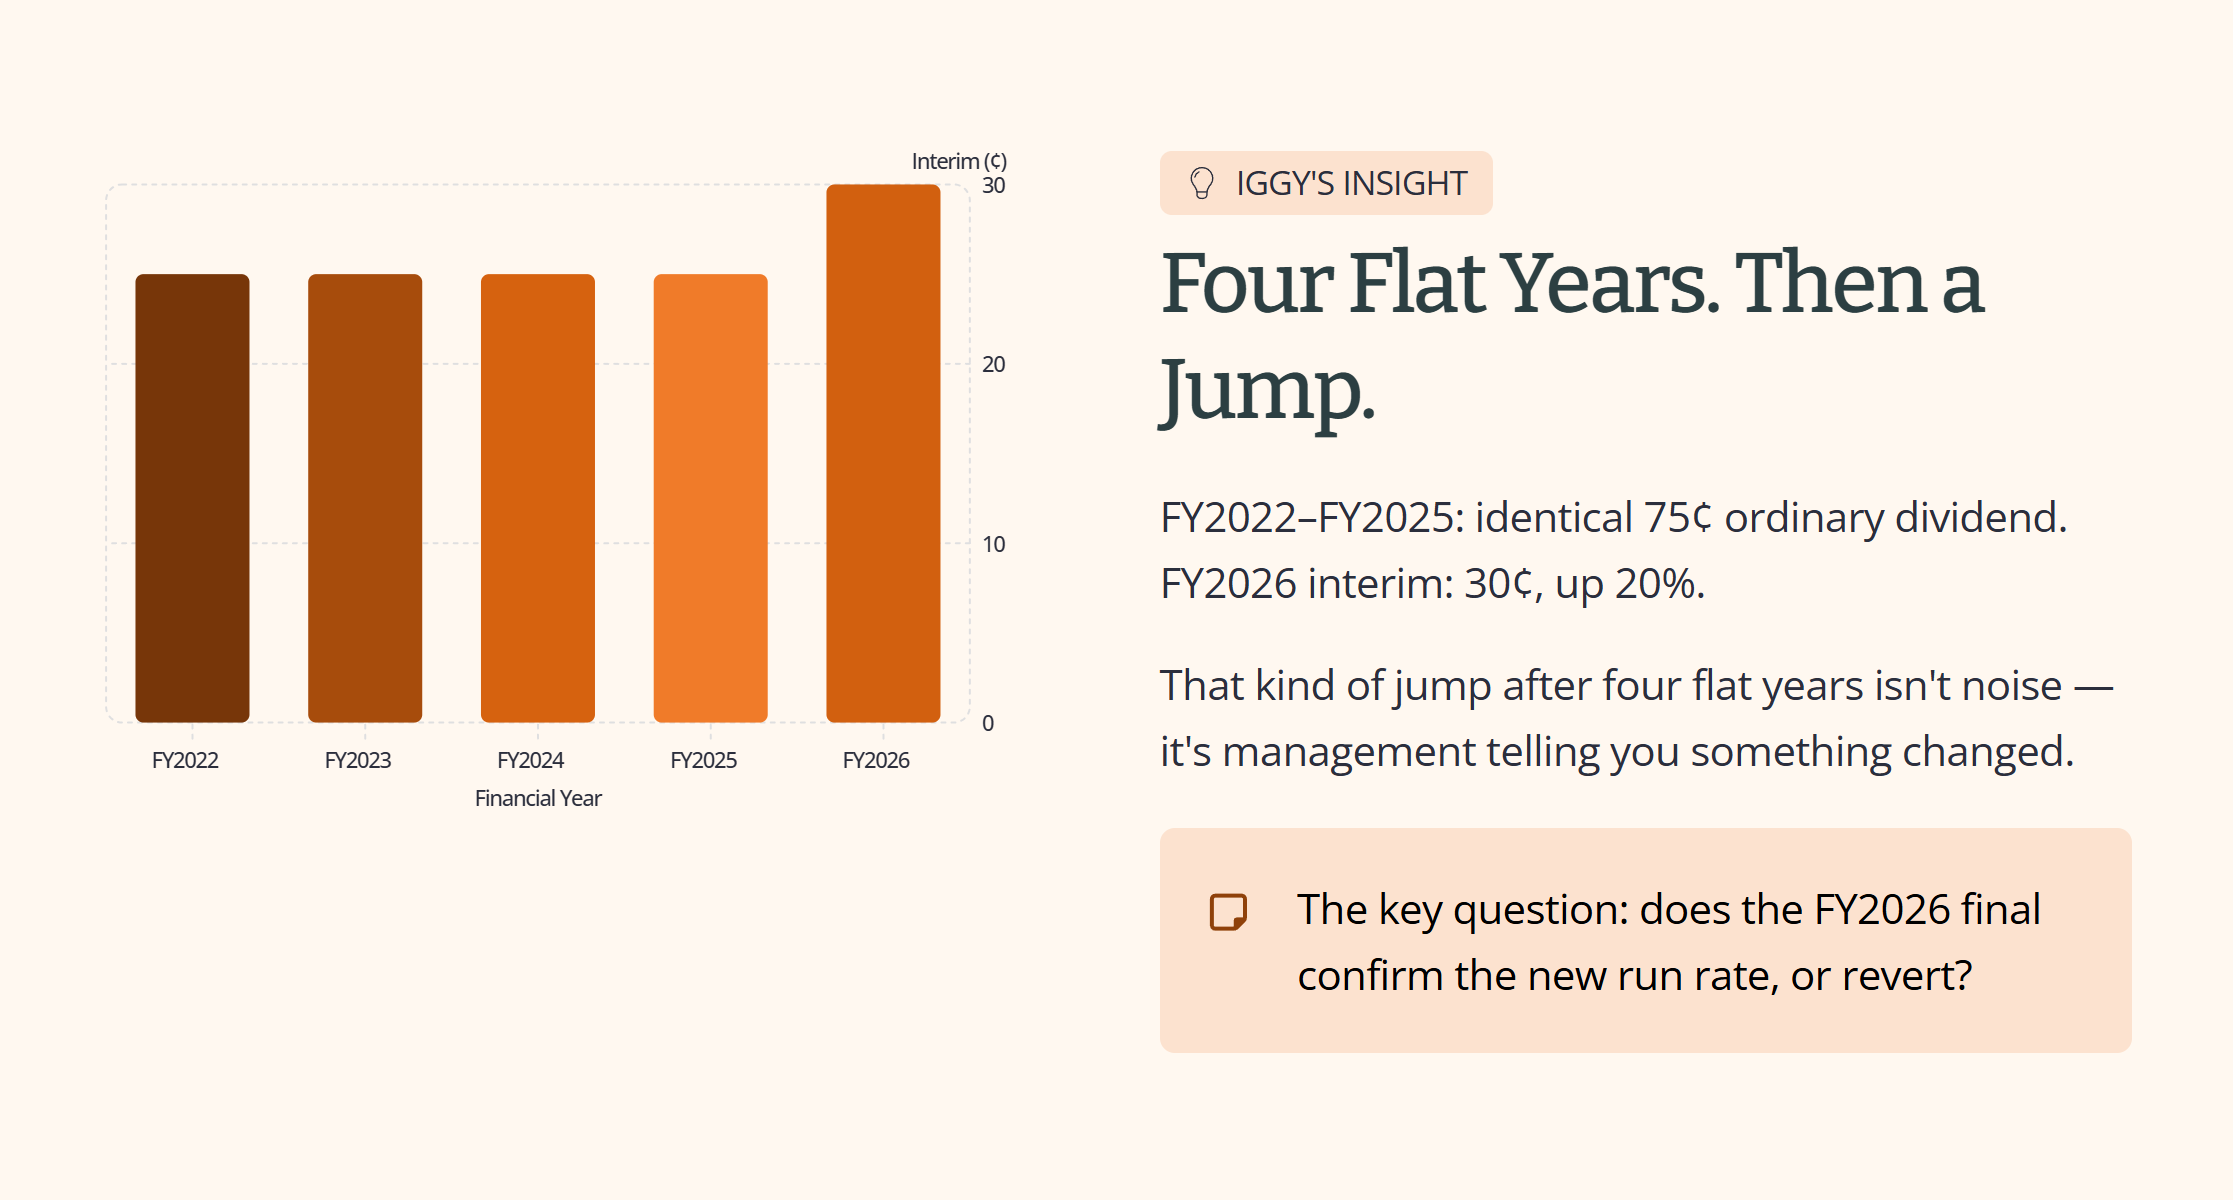
🟢Iggy’s Insight: Four consecutive completed financial years, FY2022 through FY2025, carried the exact same 75-cent ordinary dividend. Then FY2026 produced a 30-cent interim, 20% above the comparable prior-year interim. That kind of jump after four flat years isn’t noise, it’s management telling you something changed. The interesting question isn’t whether the raise is real, it clearly is. It’s whether the FY2026 final dividend, expected alongside full-year results, holds this new higher run rate or reverts. That single number will do more to confirm or break this Zone 2 call than anything else on my watch list for this name.
🔒 What’s Next
The 4.80% yield above clears my hurdle by 10 basis points. What Venture actually generated in cash from operations this half tells a very different story, and it changes how much confidence that 10 basis points deserves.
