


Why Singapore’s 2.36% Bond Yield Is Splitting the S-REIT Sector in Two
Eight REITs, one model, two very different outcomes depending on where their properties actually sit.
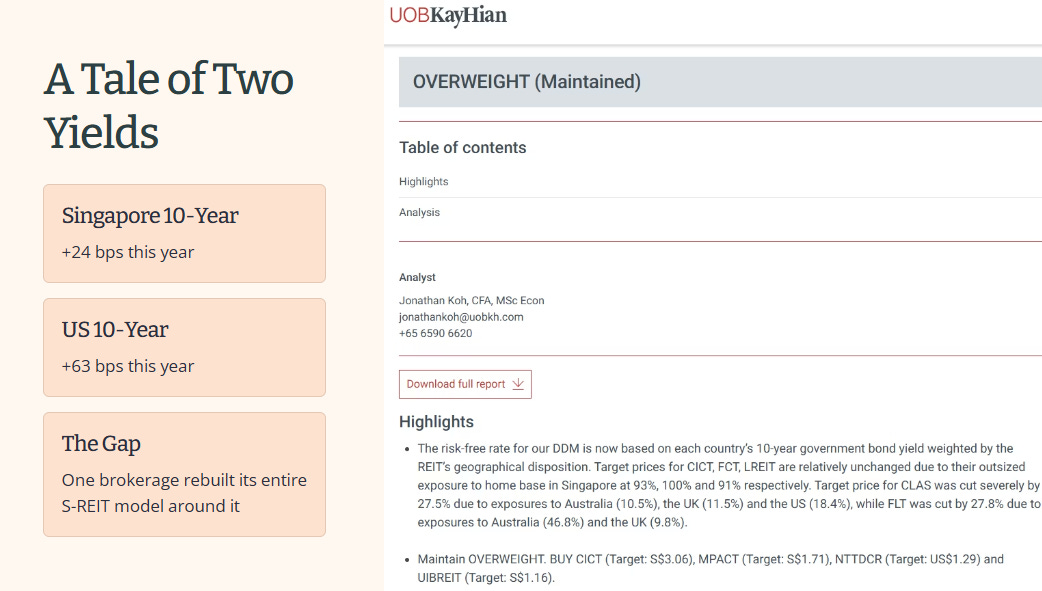
Singapore’s 10-year government bond yield has moved 24 basis points this year. America’s has moved 63. A brokerage just rebuilt its entire S-REIT valuation model around that gap between the two.
I’ve been watching REIT target price cuts scroll past all week without really understanding why some names got hit hard while others barely moved. Turns out the answer wasn’t a new earnings or occupancy shock, it was something further upstream: where in the world each REIT’s buildings actually sit. UOB Kay Hian just published a report making that connection explicit, and once you see the country breakdown, the pattern is hard to unsee.

What UOB Kay Hian Actually Changed
The Numbers Behind the Split
Angela’s Observation
The REITs That Barely Moved
The REITs That Got Cut
Same Overseas Exposure, Different Sized Cuts
So Where Does That Leave a Reader Checking Their Own Portfolio?
Angela’s Observation
What UOB Kay Hian Actually Changed
The brokerage’s report, published 10 September, said it rebuilt its dividend discount model for S-REITs by weighting the risk-free rate to the actual 10-year government bond yield of whichever country each REIT’s assets sit in, rather than applying one blanket assumption across the sector. The immediate trigger for the resulting target price moves wasn’t a change in occupancy or rental income, it was this change in how the brokerage’s model itself incorporates country-specific bond yields.
UOB Kay Hian kept its “overweight” stance on the sector overall, calling Singapore-anchored names an “oasis of calm” relative to REITs with meaningful exposure to markets where yields are climbing faster.
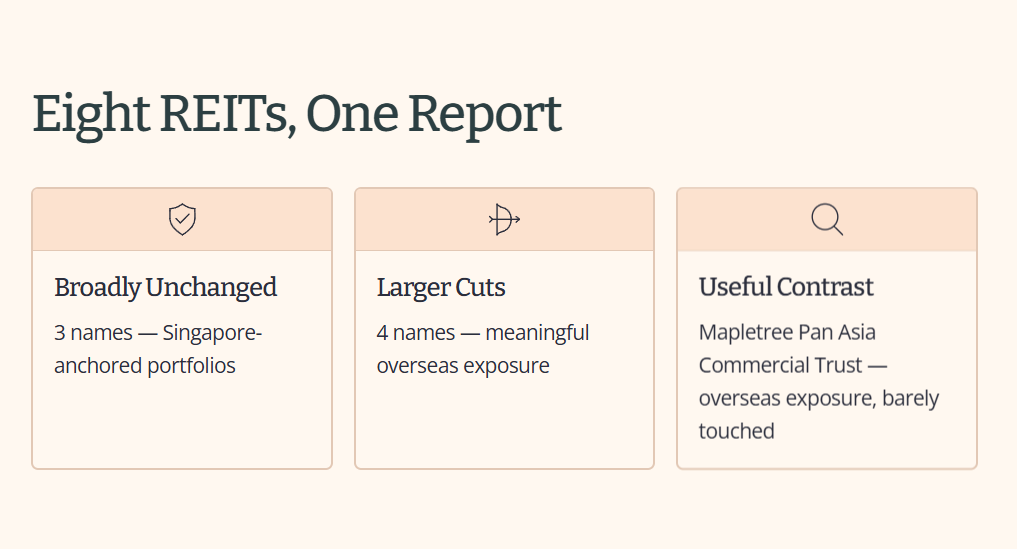
This piece focuses on eight of the names in that report: three whose target prices came out broadly unchanged, four that took larger cuts, and one, Mapletree Pan Asia Commercial Trust, included as a useful contrast, since it has real overseas exposure but was barely touched, for reasons that turn out to matter.
The Numbers Behind the Split
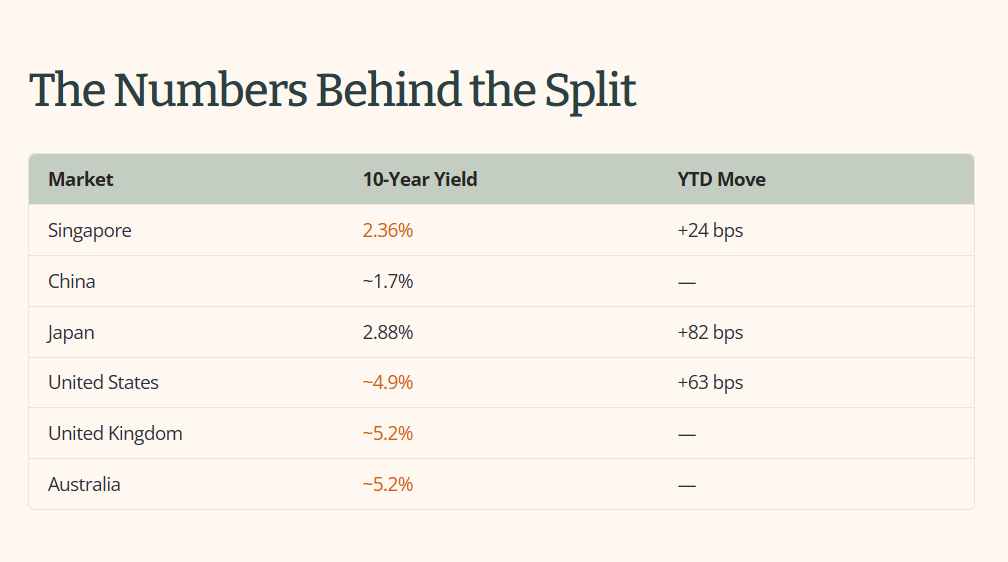
Here’s the gap doing all the work. Singapore’s 10-year bond yield has risen a comparatively modest 24 basis points this year to 2.36 per cent. The US 10-year Treasury yield has risen 63 basis points to 4.80 per cent this year, while the rounded comparative yields UOB Kay Hian used in its geographical analysis were approximately 4.9 per cent for the US, 5.2 per cent for both Australia and the UK, and 2.88 per cent for Japan, up 82 basis points. China’s 10-year, by contrast, sits even lower than Singapore’s at around 1.7 per cent.
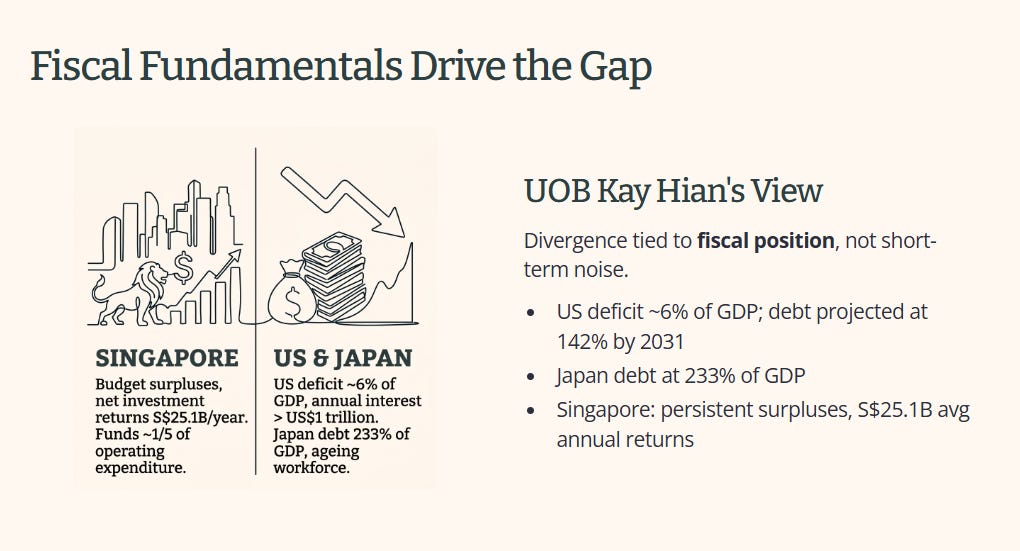
UOB Kay Hian tied the divergence to fiscal position rather than short-term market noise. The brokerage cited US budget deficits of about 6 per cent of GDP, annual interest costs above US$1 trillion, and projected government debt of 142 per cent of GDP by 2031. It cited Japan’s debt burden reaching 233 per cent of GDP this year, compounded by an ageing workforce. Singapore, by the same report’s account, has run persistent budget surpluses, with net investment return contributions averaging S$25.1 billion a year from 2021 to 2025, funding roughly a fifth of the government’s annual operating expenditure.
🟠 Angela’s Observation
I’ll be honest, before reading this report I thought of REIT valuations mostly in terms of occupancy rates and rental reversions, the things that actually happen inside the buildings. This report is a reminder that a REIT’s unit price can move for a different reason entirely: if a REIT’s properties sit in a country with a higher, faster-rising government bond yield, analysts may apply a higher risk-free rate when valuing it, which can lower the present value of its expected distributions in the model even if nothing about the rents or occupancy has actually changed. That’s a valuation effect, not necessarily a sign the REIT itself is paying more to borrow. It makes me want to ask a different question about any REIT I hold going forward: not just “how’s the portfolio performing,” but “whose bond market is this REIT actually being priced against?”
The Window Is Already Open
The Window Closes Fast. In this market, the difference between a “Sanctuary” and a “Yield Trap” is decided in a single trading session. By the time this analysis reaches you as a free subscriber, the entry window Iggy identified has already opened, and often closed.
Iggy’s Elite Investors don’t just get the report earlier. They get it when the numbers still matter, zero-day forensic breakdowns, the full “Red Zone” watchlist, and institutional-grade cheatsheets at the moment the setup is live, not after the market has already priced it in.
For S$12/month, less than two kopi and kaya toast sets at Raffles Place, you stop being the Exit Liquidity and start being the Analyst.
🔒 What’s Next
Singapore’s 2.36 per cent yield is the calm end of that table. Below the fold, the actual target price moves this model produced show exactly how wide the gap gets between a REIT sitting in that calm zone and one that isn’t, and one name that proves it’s not just about being “overseas” at all.
